“You should talk to these guys.”
— Serving Clients Nationwide Since 1979 —
Invoice factoring for Nashville, Middle Tennessee, and Tennessee businesses that bill B2B customers on terms.
(also called accounts receivable factoring or receivables factoring)
Orange Commercial Credit is an independent, privately held nationwide direct factoring company. We work directly with Nashville and Tennessee businesses that bill other businesses on terms.
We buy approved unpaid invoices for trucking, staffing, manufacturing, and other B2B companies so you can get paid before your customer’s 30, 60, or 75-day terms end.
After account setup, customer approval, invoice verification, and required backup, we usually send the advance within 24 hours.
Before you decide, we show the numbers in writing: the advance, any reserve, the fee, and funding timing.
A factoring company buys approved unpaid B2B invoices so a business can get paid before its customer pays on terms.
Searching for Nashville factoring companies can mean two different things: finding companies with a Nashville-area office, or finding companies that can factor invoices for a Nashville business. Those are not always the same companies.
A map result can show which companies list a Nashville-area location. But that answers only the first question.
No. A factoring company does not need a Nashville office to factor approved invoices for a Nashville business. If meeting in person is important to you, a local office gives you that option.
Customer approval starts with commercial credit review and payment-history information. At Orange Commercial Credit, our credit managers use national commercial credit databases to review your customer. We also verify the invoice and the backup paperwork tied to the completed work. Those checks do not require a Nashville office.
To compare companies that can factor invoices for a Nashville business, look at local-office providers and national factoring companies serving Nashville. Then ask who buys approved invoices directly, what industries each company specializes in, and who answers after setup.
Orange Commercial Credit buys approved invoices directly. We specialize in trucking and freight, staffing companies that need payroll funding, and manufacturers. We also review invoices from other B2B companies, including approved logistics, warehouse, airport-cargo, industrial-service, commercial-service, and entertainment-support receivables. After setup, you work with a dedicated account executive who knows your business and paperwork. One customer and one invoice can start the review.
You may have heard about us from a friend, or you may be comparing Nashville factoring companies after a search. However you got here, the pressure is usually the same.
You need the money before your customer pays on
30, 60, or 75-day terms.
The work’s already done. The invoices are out. And your bills are piling up while you are left waiting.
Trucking. Staffing. Manufacturing.
Different work. Same wait.
Your customer wants 30, 45, or even 60-day terms. To win the business, you agree. No matter the terms, you still have bills to pay.
Payroll, fuel, insurance,
materials, equipment, repairs...
The bills keep coming while you wait out those terms. You can put expenses on a card while you wait, but the card bill comes due long before your customer pays.
Wait too long and you’re the one
stuck with late fees or interest.
That pressure is why the lowest advertised rate is not enough. Before you choose, compare what each company will put in writing for one real customer and one real invoice.
Nashville search results can mix local office pages, national direct factoring companies, freight and staffing specialists, transportation-management firms, entertainment business-management firms, risk-management or software companies, brokers or referral listings, and bank-backed or commercial-finance providers offering a different product.
Headlines may mention 3–5 day setup, quick pay, fast approval, same-day or 24-hour funding, no-upfront-fee wording, high advance rates, recourse or non-recourse programs, fuel or carrier tools, local service, or national access. Those claims do not all describe the same product or the same point in the review.
Before you compare the headline, identify who funds the invoice and what the written quote says for one real customer and one real invoice.
Third-party medical receivables and most construction invoices are different categories from the approved B2B receivables Orange Commercial Credit generally factors.
After you confirm the industry fit, compare the complete written cost and terms, not only a headline rate, quick-pay claim, or local-office label.
The written numbers are what let you compare the quote without guessing.
With Orange Commercial Credit, you won’t have to chase three people to find out what’s happening with your invoice. After setup, you work with a dedicated account executive who knows your business and paperwork, backed by an experienced team.
One transportation client described that account relationship this way:
“We have daily email contact with April and she’s so responsive to our needs.”
—Jennifer, Manager and Client Since 2014, Transportation Company
Use the table below to compare the claims visible in Nashville search results with the parts of the factoring relationship that affect every invoice.
| What you see in search | What to check before you choose |
|---|---|
| Nashville office, West End listing, 10th Avenue South listing, Charlotte Avenue listing, local phone number, map listing, reviews, or ratings | A meeting is one moment. Compare what happens with every invoice: who knows your account, who reviews the paperwork, who answers when something is missing, and what the written quote shows for the advance, any reserve, fee, and funding timing. |
| 3–5 day setup, quick pay, fast approval, same-day funding, or no-upfront-fee wording | Whether the timing refers to application review, account setup, customer approval, invoice verification, required backup, or the actual advance, and what other timing conditions are shown in writing. |
| Freight specialization, freight-management claim, fuel card, fuel bundle, app, load board, or carrier-service offer | Whether the broker or shipper can be approved, the load paperwork supports the invoice, and the extra service changes fees, minimums, invoice choice, agreement terms, switching terms, or who answers after setup. |
| Payroll funding, staffing factoring, or back-office support offer | Whether the company is buying approved unpaid staffing invoices or offering payroll processing, tax filing, timekeeping software, recruiting support, or another service with different costs and responsibilities. |
| Entertainment business management, artist finance, risk management, software, consulting, or commercial lending | Whether the provider is buying approved invoices, managing business finances, consulting, managing risk, selling software, arranging a loan, or offering a different service. |
| Truck finance, equipment finance, purchase-order funding, asset-based lending, working-capital loan, or business credit line | Whether the product is invoice factoring for completed B2B work or a different finance product with different collateral, repayment, reporting, payment instructions, and exit terms. |
| Recourse or non-recourse factoring | What the label covers, what it does not cover, and when you could still be responsible. |
| Payment-instruction language | What the written agreement says about payment instructions, who answers invoice questions, and what happens when payment is late, disputed, or short. |
| Broker, marketplace, advisory service, or referral listing | Who actually funds the invoice, who services the account, whose agreement you sign, and who answers questions after setup. |
Nashville results can include local-office signals such as Nashville office listings, West End listings, 10th Avenue South listings, Charlotte Avenue listings, local phone numbers, map listings, reviews, or ratings. They can also include regional Tennessee providers, national direct factors, freight and staffing specialists, entertainment business-management firms, risk-management or software companies, brokers or referral listings, commercial-finance companies, bank-backed providers, and other finance-adjacent services.
The table below shows what each provider type usually means and what to verify: who funds the invoice, whose agreement you sign, who services the account, and what the written quote shows.
| Provider or listing type | What it usually means | What to check before you choose |
|---|---|---|
| Local Nashville office or Tennessee provider | May show a Nashville office, West End listing, 10th Avenue South listing, Charlotte Avenue listing, local phone number, map result, reviews, or a Nashville-specific factoring page. | A local office is not needed. Check who reviews the customer, verifies the invoice, sends the advance, and answers after setup. |
| National independent direct factoring company serving Nashville | Reviews the customer and invoice, factors approved invoices, sends the advance, receives the customer’s payment, and services the account without requiring a Nashville office visit. | Whether one customer and one invoice are enough to start and whether the quote shows the advance, any reserve, fee, payment instructions, funding timing, agreement terms, invoice choice, and account support. |
| Freight or trucking factoring provider | Usually focuses on carriers, brokers, shippers, rate confirmations, PODs, bills of lading, freight-management support, quick-pay wording, fuel-related services, apps, load boards, or carrier tools. | Whether the broker or shipper can be approved, whether the load paperwork supports the invoice, and whether extra services affect fees, minimums, invoice choice, agreement terms, switching terms, or who answers after setup. |
| Staffing factoring company or payroll funding provider | May focus on staffing agencies, approved timesheets, weekly payroll, payroll processing, back-office support, tax filing, onboarding tools, or timekeeping software. | Whether the service is invoice factoring, payroll processing, back-office administration, a payroll loan, or another product with different costs and responsibilities. |
| Entertainment business-management, artist-finance, or music-industry service provider | May manage cash flow, reporting, taxes, business affairs, or financial administration for artists, musicians, touring companies, venues, vendors, or entertainment businesses. | Whether the provider is buying approved B2B invoices or offering business management, consulting, bookkeeping, tax support, or another service. |
| Risk-management, software, consulting, or commercial finance provider | May provide risk analysis, software, transportation consulting, energy-sector advisory work, commercial lending, or another finance-adjacent service. | Whether the provider is buying approved invoices, arranging financing, managing risk, selling software, consulting, or offering another service with different costs and responsibilities. |
| Broker, marketplace, advisory service, or referral listing | May introduce you to one or more factoring companies instead of funding and servicing the account directly. | Who actually funds the invoice, whose agreement you sign, who services the account, and who answers questions after setup. |
| Bank-backed, secured loan, asset-based, equipment finance, or purchase-order funding provider | May offer factoring, asset-based lending, secured loans, equipment finance, inventory finance, purchase-order funding, working-capital loans, or business credit lines. | Whether the offer is invoice factoring for completed B2B work or a different product with different collateral, repayment, reporting, payment instructions, and exit terms. |
Orange Commercial Credit fits the national independent direct factoring company category.
Once you know what each claim means, check what kind of company or listing made it and who actually reviews and funds the invoice.
The details matter because the rate alone does not tell you what happens before funding or after your customer pays. A written quote should show the customer review, invoice review, advance, any reserve, fee, payment instructions, funding timing, agreement terms, invoice choice, and account support.
We're Orange Commercial Credit. We buy approved unpaid invoices for work you’ve already done. It’s called invoice factoring, and we’ve been doing it since 1979.
Through recessions, slow seasons, and the ups and downs of every business cycle, Orange Commercial Credit has kept clients funded so payroll, fuel, and repairs get paid even when your customers’ payments are still weeks away.
You send us your customer's invoice and once it's approved, we send you most of the money up front.
This up-front payment is called an advance. Depending on your industry, it can be as high as 98% of the invoice.
When your customer pays and the payment posts to our bank, the written agreement controls how any reserve is handled, less the factoring fee, which can range from 1.25% - 5%.
You choose which invoices to sell. Use it when you need it, skip it when you don’t.
We’ve been through decades of change, but one thing never changes: your bills don’t stop. That’s why your money shouldn’t wait.
Over the years we’ve worked with trucking companies, staffing firms, service providers and manufacturers just like you. Many have been with us five years or more.
They stay because they value the service and the ability to factor approved invoices when the account and invoice qualify.
They have one dedicated account executive who is backed by an experienced team ready to answer all their questions.
Most of our business comes from referrals. Our clients refer because they know their friends will get the same service they do.
A produce hauler told us what it feels like working with OCC:
“We love OCC! They have taken care of us since 2021. We have the pleasure of working with our account rep. She is such a big help. Always quick to respond to any questions or inquiries we may have. She is always available and I know that I can always count on her. She’s the best! Quick payment, great rates, excellent communication. A trusted company. Highly recommend.”
—Mariya, Owner-Operator, Produce Hauler
A trucking owner told us how she first came to OCC:
“I turned to my friend Mike for advice and he referred me to his factor… OCC. She reviewed my paperwork and explained step by step what I needed to do including outlining who to contact, what numbers to reference and what I needed to ask.”
—Alyssa, Owner, Long-Haul Trucking Company
After account setup, customer approval, invoice verification, and required backup, we usually send the advance within 24 hours.
Factoring Invoices Since 1979
Trucking, staffing, and manufacturing companies in
Nashville and across Tennessee use us when the wait gets too long.
One customer. One invoice. One call.
You get a person, not a menu:
1-800-231-3878
The only way this works is if your customer’s good for it. That’s why our credit check matters.
We’ve been doing this since 1979, and many of our credit team members have been here 10+ years. They know how to check credit right.
We focus on getting you paid faster on approved invoices.
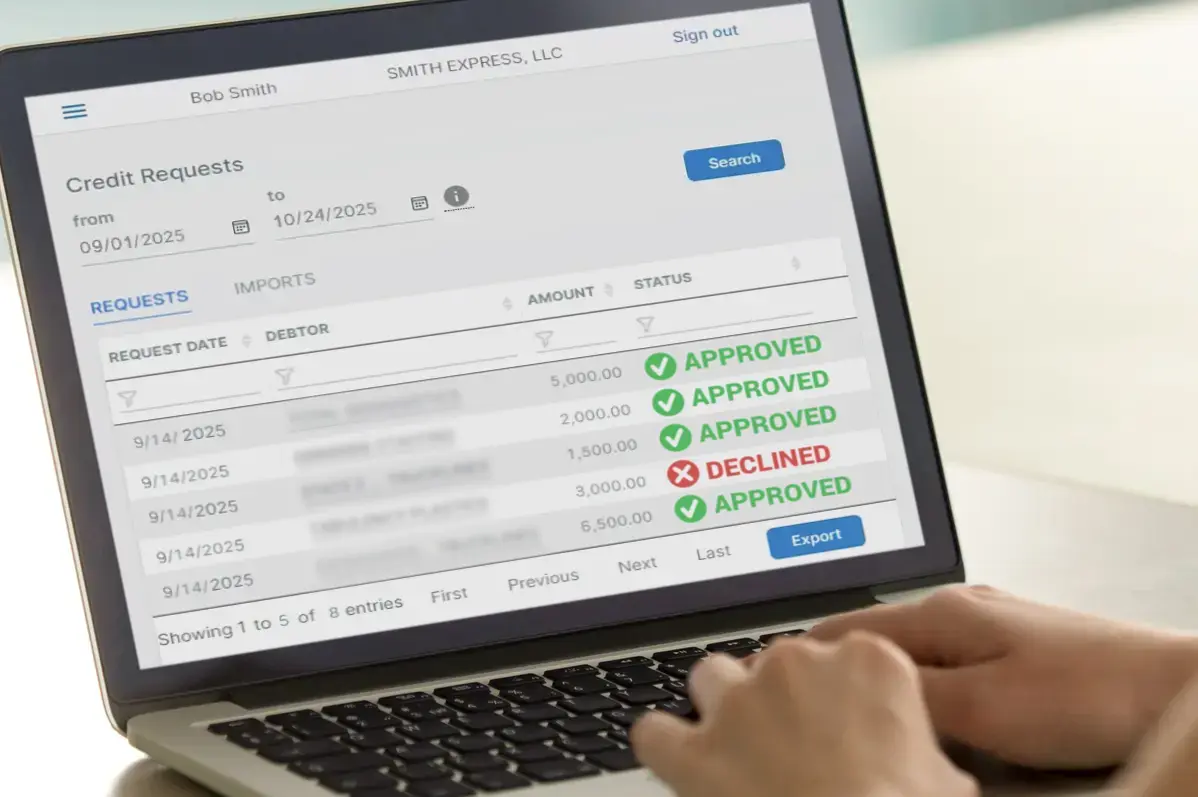
It’s one thing to hear you’ll get paid...
Here’s what happens, step by step, from the time you send an invoice until the final payment clears.

In invoice factoring, the first thing we do is check your customer’s credit. We pull their payment history up front—even before you send us an invoice—because that’s how we decide if we can buy the invoice from you.

Once they're approved, you send an invoice, and our team then reviews the supporting paperwork that goes with it.
Your written quote and agreement explain where your customer sends payment and any verification steps required before funding.
The work you completed and the invoice amount do not change. The written payment instructions explain where your customer sends payment.

The last step is the funding, the part you care about most.
That’s when we send the advance.
On every funding you’ll see:
Trucking advances can be as high as 98% of the invoice. After account setup, customer approval, invoice verification, and required backup, Orange Commercial Credit usually sends the advance within 24 hours.
If a reserve applies, the written quote shows how much is held back. The written agreement controls how that reserve is handled after the customer pays and the payment posts to our bank.
Before you decide, ask how any reserve is handled under the written agreement.
The discount fee depends on:
Whatever the case, you see the advance, any reserve, the fee, and funding timing before you decide.
That's how our factoring works.
Ready to see your numbers? You always see the advance, any reserve, and our fee before you decide. No surprises. Call and we’ll walk you through one invoice on the phone:
1-800-231-3878
The difference with us? We’re independent so we can set your terms the way you need them.
We don’t answer to outside investors. We’re privately held with no board calling the shots. We’re business owners too.
Your terms come from us, and no one else.
We know what it takes to meet payroll and keep the lights on. And we also know that every business is different. We don't drop numbers into a formula.
We base terms on what we see in your invoices and your customers, not on a one-size-fits-all chart.
One flatbed hauler said it best:
“It doesn’t matter if you bring $1 or a million, I guarantee you these people will treat you as a family member. We will always see these people as a great place for financial support and great customer care.”
—Rico, Flatbed Hauling
In the end, it comes down to trust. Who do you want to rely on when the bills can’t wait? With us, it starts simple: pick one customer, one invoice, and make one call.
You’re probably asking: So how would this work in my business?
The answer depends on the work you do.
We don’t fund most types of construction, third party medical receivables or consumer invoices. But we have funded companies across more than 50 industries.
We fund invoices for work that’s already done. The goods are already delivered, but your customer’s on terms.
The real issue is when the wait drags well beyond 30 or 45 days.
Let's walk through a few examples in trucking, staffing, and manufacturing, the industries where this matters the most.
Trucking advances can be as high as 98% of the invoice.
Orange Commercial Credit provides freight factoring for carriers that have delivered the load and invoiced a broker, shipper, or other B2B customer. We buy approved freight invoices so carriers can have money for fuel, repairs, payroll, and other bills before the broker or shipper pays. Freight factoring is also called trucking factoring.
Trucking companies are Orange Commercial Credit’s largest client group. For Nashville, Middle Tennessee, and Tennessee carriers, our team reviews broker credit and the invoice packet: signed rate confirmation, bill of lading or POD, invoice, and paperwork for extra charges such as lumper fees or detention.
You’re here because you’re done waiting to get paid. At Orange Commercial Credit, we buy invoices so carriers have money for expenses that won’t wait: repairs, fuel, and detention or lumper fees. This is called trucking factoring. You may also hear it called freight factoring or freight bill factoring.
We work with all of them every day
and the story's always the same.
The load’s already hauled. The paperwork’s in. The only thing missing is the money in your account.
And the paperwork looks different depending on the job.
However you haul it, the wait is the same.
The load’s delivered, the paperwork’s in, and you’re still not paid.
Meanwhile, fuel, payroll, and repairs are due now. That’s when you factor an approved invoice and we send the advance.
You’ve seen the ads: same-day funding, fuel cards, mobile apps, even 24/7 payouts. That’s all fine.
So the real question is:
Will the money actually
be there when you need it?
After account setup, customer approval, invoice verification, and required backup, we usually send the advance within 24 hours.
And what about brokers?
You may not know if one’s been paying slow before you book the load.
That’s what our credit team does every day. We flag slow payers before you haul, so you don’t waste miles on a load that won’t pay.
We’ve been doing this since 1979. Many on our credit team have been here more than ten years.
That experience helps our team review the customer, invoice, and backup without making you guess what comes next.
Friday payroll comes due. Fuel card drafts this week. The truck note hits this month.
And the shop won’t release a truck until the repair’s paid. Plus, you need tires and have insurance renewals.
Carry a balance on your card, and the interest adds up.
Fuel bills spike, and drafts hit your account whether or not a broker’s check has cleared.
None of those bills wait.
You need to get paid.
If your freight operations converge at the I-24, I-40, and I-65 split and the heavy industrial lanes along Cockrill Bend Boulevard, you are working one of the busiest freight pictures in Middle Tennessee.
That run can also pull in Whites Creek Pike, Briley Parkway, and James Robertson Parkway when drivers are trying to stay moving around the west side and into the East Bank side of town.
The I-24 Southeast Choice Lanes corridor is part of that Nashville picture now. TDOT says the stretch between I-40 and I-840 carries more than 174,000 vehicles a day, so when that route backs up, runs take longer and pickups or deliveries can get pushed back.
If your runs reach the airport side, Donelson Pike is part of the route too. TDOT shifted traffic onto the new diverging diamond interchange there on June 10, 2025, and the full interchange project is scheduled through August 2027, so that side is still a live traffic variable for BNA and the surrounding cargo lanes.
When the split backs up, Donelson Pike slows down, or airport-side traffic bunches up, runs take longer, fuel gets used, and the next pickup or delivery can get pushed back.
If the delivery window closes, the load waits.
You still have fuel to buy.
Payroll is Friday. Your customer is paying on 30, 60 or 75 day terms.
A fleet owner put it this way:
“Amazing people working at this company! Always a phone call away always eager to help and always getting the issues solved. Great % rates and overall great people starting from managers to accountants and assistants. Been working with them for over 4.5 years with no problems or complications what so ever.”
—Vitaliy, Interstate Freight Carrier
An intermodal freight fleet owner told us what OCC meant for his business:
“Orange Commercial Credit (OCC) was instrumental in our growth from the very beginning. They not only understand the trucking industry but also specialize in the intermodal and drayage business. The funding is quick, the relationships are deep, the rates are fantastic, and the trust earned is invaluable. I have been able to personally recommend OCC to many of our Clients over the past years and have always heard great feedback in return. Thank you OCC for your commitment and friendship. Clients like me really do appreciate it!”
—Michael S., President, Intermodal, Client since 2013
A long-haul carrier told us why the credit check matters:
“OCC is an exceptional factoring company! Not only do they help us with our invoices, but also advise us on broker credibility, ensuring that we are getting paid for our work. I would like to express my sincere appreciation to my AE for her prompt responses to my inquiries. It makes a real difference.”
—Tom A., Long-Haul Trucking
Tom’s quote shows what a fleet counts on with credit checks. But when it’s just you and your truck, it’s fuel, repairs, insurance, and the bills waiting at home. All on you.
Fuel card drafts hit every week. The truck note’s coming due. Add shop repairs and home bills. Waiting 30–45 days for a broker to pay just doesn’t cut it.
After account setup, customer approval, invoice verification, and required backup, we usually send the advance within 24 hours.
Here’s how another owner-operator put it after using OCC for years:
“I'm a small carrier owner operator.
I've been using Orange Commercial Credit for about 4 years now and I couldn't be more happier with the service provided by OCC.
OCC is very fair with their rate and they pay out very quickly (next day).
Their staff is great, very professional and nice.
I recommend OCC for all carriers who need a factoring company.”
—Ezechiel, Owner-Operator, OCC client since their first load
Ezechiel’s an owner-operator, and the bills don’t wait any less when you’re hauling hot shot loads.
Hot shot runs are smaller, but the bills still stack up just as fast.
Whether you're in an F-350, a Ram, or a Duramax with a gooseneck or bumper-pull, one stretch of repair and fuel bills can drain your cash fast.
You could really use that new Big Tex tandem dual wheel, but trailer payments stack up fast.
And if a broker’s been paying slow, you hear it from us before you waste the trip, not later.
A hot shot driver explained why she sticks with OCC:
“Orange Commercial Credit is an excellent company to work with. They offer exactly what we need to run our trucking company, we always know what brokers are safe to work with due to Orange’s credit check feature. Staff is always friendly and helpful. I have never had a bad experience with our assigned Account Executive or any other staff member for that matter, the whole team is great!”
—Crystal, Hot Shot Trucking
You’ve done the work. You shouldn’t be waiting a month to see the money.
Most clients start with just one customer, one invoice, and one call to us. Even if you just have a question, call us. We'd be happy to talk with you.
If you’re running loads in or out of Nashville or anywhere in Tennessee, we can walk through one invoice on the phone:
1-800-231-3878
We’ve been checking broker and shipper credit since 1979.
An advance can be as high as 90% of the invoice.
For Nashville staffing agencies, we review the invoice, approved timesheets, service agreement, and any customer approval needed before funding.
Healthcare, light-industrial, warehouse, airport cargo, logistics, plant support, and industrial staffing firms still have to pay W-2 wages, payroll taxes, workers’ comp, benefits, and compliance costs before customers pay.
Once the customer is approved, the timesheets are verified, and the account is set up, we usually send most of the money within 24 hours so payroll can run on time.
Payroll funding in Nashville, TN can mean different things. Some companies want payroll processing, HR support, back-office staffing services, or a short-term payroll loan. Orange Commercial Credit is different: we fund approved B2B invoices so staffing, logistics, warehouse, industrial, and other service companies can pay workers before customers pay.
Orange Commercial Credit is not a payroll processor, PEO, or short-term payroll lender. We fund approved invoices so payroll can get paid while your customer is still on terms.
If you run a staffing agency, payroll means two things: the recruiters in your office and the workers already out on site.
Timesheets get signed, checks go out every Friday, and customers may not pay for 30, 60 or more days.
The hours are already worked. Payroll’s due. The money isn’t in yet.
However you staff it, the work is done and you’re still waiting to get paid.
And it’s never just wages. You've got:
If your staffing focus is on Skyway Industrial Park and the light-industrial corridors of Antioch and La Vergne, you are filling some of the main warehouse and freight-side shifts in Middle Tennessee.
That hiring can also pull in Murfreesboro Pike, Bell Road, Harding Place, and the Smyrna side when crews are trying to get into second-shift and early-morning jobs on time.
The I-24 Southeast Choice Lanes corridor is part of that picture now. TDOT says the stretch between I-40 and I-840 carries more than 174,000 vehicles a day, so when that route backs up, workers can show up late and shift-start coverage can get harder to hold.
WeGo Route 55 on Murfreesboro Pike is part of that same staffing picture for some Antioch-side workers, and WeGo Central still matters when workers have to transfer downtown before the shift starts.
On the north and east side of town, the labor draw can also reach toward Dickerson Pike, Bordeaux, and the East Bank side of Nashville. Metro describes the East Bank as a 550-acre area running all the way to I-24, so that side can carry more weight in the same broader commute picture.
When interstate traffic backs up, a bus runs late, or a transfer gets missed, workers can show up late and shift coverage can get thin fast.
If a shift isn’t filled, the job doesn’t happen.
You still have rent and insurance to pay.
Payroll is Friday. Your client is paying on 30, 60 or 75 day terms.
Without funding, some owners try to stretch their own payables or pay bills with credit cards. Others dip into personal savings, just trying to bridge the weeks until customers finally send payment.
A staffing owner explained how OCC let him take on more customers:
“I can always count on them. Orange Commercial has helped me take on clients I normally could not afford to take. The setup process with them was easy. They let you choose which clients you want to factor. Pricing is reasonable for the industry. Customer service is great and I can always count on them to send me funds when I need it.”
—George, Owner and Client Since 2016, Staffing Company
A staffing owner told us how OCC changed his cash flow:
“As a staffing company owner, I heavily rely on cash flow to keep my operations running smoothly and meet payroll, OCC's factoring process is incredibly streamlined and hassle-free. Their newly implemented online platform is user-friendly, making it easy for me to submit and track invoices. This new system allows me to receive funds quickly and efficiently, greatly improving my cash flow management. I highly recommend them.”
—Joe, Owner, Staffing Company,(Client since 2018)
And that’s how factoring works in staffing. A lot of owners call it payroll funding. Payroll runs every week, along with taxes, insurance, and benefits. With Orange Commercial Credit, approved staffing invoices can be factored so payroll can be covered before the customer pays.
You’ve made payroll. You shouldn’t be carrying it for weeks while customers take their time.
You send the invoice and approved timesheets; we review and send funds so your people get paid on time, even when customers take 30–60 days to pay you.
Most agencies start with just one customer, one invoice, and one call to us.
Or if you have just one question, call us now and get an answer:
We advance on your staffing invoices so you can run payroll,
pay taxes, and cover benefits.
An advance can be as high as 90% of the invoice.
For Nashville manufacturers, we may review the invoice, purchase order, bill of lading, packing list, delivery proof, work ticket, or signed QC paperwork tied to the completed order.
Nashville and Middle Tennessee manufacturers may be buying raw materials, paying suppliers, scheduling shop work, shipping finished goods, or waiting on customer payment from plant, warehouse, industrial, and other commercial accounts.
I-24, I-40, I-65, I-840, the Smyrna–Murfreesboro corridor, Donelson Pike, BNA cargo lanes, and the wider Middle Tennessee freight network can all affect when raw materials or finished goods reach the next production step.
After account setup, customer approval, invoice verification, and required backup, Orange Commercial Credit usually sends the advance within 24 hours.
Staffing firms feel it every Friday. Manufacturers do too, just with different bills.
If your manufacturing work runs through the Smyrna-Murfreesboro corridor, plant traffic can center on Nissan Drive, Sam Ridley Parkway, and Enon Springs as materials and finished goods move in and out of the Smyrna side.
That work can also pull in Waldron Road, the I-24 Southeast Choice Lanes corridor, and the airport-side industrial lanes when inbound parts and outbound loads are trying to stay on schedule.
TDOT says the stretch of I-24 between I-40 and I-840 carries more than 174,000 vehicles a day, so when that route backs up near Smyrna, inbound materials can show up late and outbound loads can get pushed back.
If your freight also reaches the airport side, Donelson Pike is part of the picture too. TDOT shifted traffic onto the new diverging diamond interchange there on June 10, 2025, so that side is still a live variable for plant traffic and cargo access.
Plant routes also tie back into La Vergne, Lebanon, Wilson County, and the I-840 loop, where the same lanes can carry appliance, component, and industrial freight from receiving to shipment.
When I-24 traffic stacks up, airport-side access slows down, or a pickup gets delayed, inbound materials can show up late, outbound loads can get pushed back, and the line can end up waiting on the next part or truck.
If materials are late, the production line slows.
Power and utility bills keep running.
Payroll is Friday. Your customer is paying on 30, 60 or 75 day terms.
Suppliers want to be paid in 15 to 30 days. Customers take 45 to 60 days and sometimes longer. And they don’t release payment until every piece of paperwork lines up:
By the time you deliver and gather it all, you’ve already cut the checks weeks ago. And you’re still waiting on their payment.
And this is where factoring
helps in manufacturing.
You send the invoice with the paperwork. We review the customer, invoice, and required backup. After account setup, customer approval, invoice verification, and required backup, we usually send the advance within 24 hours.
A pallet manufacturer told us how OCC became part of their growth:
“I’ve been working with OCC for over 9 years now and they’re like a partner for me.
I could not have grown my business this quickly without them!
My account executive is great.
I get credit checks done same day on new business and have never had a complaint from any customer.”
—E.H., President, Pallet Manufacturer
A machine shop owner found that factoring with OCC was "very easy to work with":
“Finding out about OCC has helped keep my business operating with the cash flow I am now receiving. Within a day the money is in my account. During the whole process, OCC was very easy to work with. They made sure I was completely confident and work with me step by step, and the staff is very patient. I would recommend them to any business. Once you start with OCC, you will also be recommending them.”
—Val, Owner and Client Since 2017, Machine Shop
Whether it’s pallets, plastics, machining or food processing, if you’ve already delivered and sent the invoice, you don't need to be waiting 45 to 60 days for payment.
With us, you send the invoice with the backup. After account setup, customer approval, invoice verification, and required backup, we usually send the advance within 24 hours.
Pull one invoice from one customer,
and give us a call.
We'll walk you through it.
Call us today.
Manufacturers in Nashville and across Tennessee use us when customer terms run long.
Here's another benefit to factoring
you may not be aware of:
If you’re a pallet manufacturer sending a quote, a distributor supplying parts, or a service firm chasing contracts, you’ve heard it:
“Can you give us Net-30?”
Sometimes Net-45. Buyers ask for it every day. And if you can’t offer it, they move on. With factoring in place, you can say yes without tying up your own cash.
Longer terms can:
What matters most is whether your customer is creditworthy, whether the work is complete, and whether the invoice and backup paperwork can be reviewed and verified.
Things like tax liens or pledged invoices can slow things down, but we'll talk it through with you.
We’ll tell you what we can review and what the next step is before you decide.
Call us and we'll go over one of your customer's invoices together.
At Orange Commercial Credit, our portal shows every invoice and payment—status, paperwork and credit—so you always know where you stand.
You don’t have to wonder
if a payment was posted right.
Your paperwork is handled by our team who’ve been here on average 10 years and know your paperwork and your customers.
At Orange Commercial Credit, you get a dedicated account executive. They know your account, your business, and your paperwork, backed by an experienced team.
You talk to the same person who knows your account and can explain what is complete and what still needs review.
A logistics company shared what their experience with OCC has been like:
“We have been with OCC for the last 3 years and have had a great relationship. OCC has been a very important part in our business. With their quick credit information on new prospect customers is the key to eliminate any accounting issues.
"We submit our invoices through their scanning program and are funded same day with no problems.
"We have not had any problems or complaints from our customers as they are very kind and professional to them.
"I highly recommend OCC if you are looking for a reliable and honest Factoring Company.”
—Mary, Operations/Accounting, Logistics Company
No. Invoice factoring isn’t a loan. You sell an invoice for work already done, so there’s no new debt. It’s money that was already owed to you. You just get it sooner.
Factoring fee range: 1.25% - 5% (varies by deal).
The discount fee is a percentage of the invoice. How much depends on your industry, how fast your customer pays, your customer’s credit and the dollar amount of invoices you sell us.
You always see the advance, any reserve, the factoring discount fee, and funding timing in writing before you decide.
If a reserve applies, ask what the written agreement says about how it is handled after your customer pays. Ask for every applicable charge in writing before you decide.
Ask whether any transfer, portal, invoice-submission, due-diligence, termination, or other charge can apply. The written proposal should show the charges for your account before you decide.
This list is here so the numbers don’t surprise you later.
If you only ask three, start here:
Full checklist:
1) Advance rate:
This is what you get up front. A lower advance can mean you’re waiting on more of your own money until your customer pays.
2) Factoring fee:
Ask what the fee covers: per 10 days, per 30 days, daily, or flat. If it’s tiered, ask for the full tier schedule in writing.
3) Recourse period (how long the invoice can stay open):
Ask what happens if your customer still hasn’t paid by then.
4) Recourse or non-recourse (who takes the loss if your customer doesn’t pay):
Ask what “non-recourse” covers — and what it doesn’t.
5) Customer Credit Concentration limits (how much they’ll fund for one customer):
Ask what the limit is if one customer is a big share of your billing.
6) Reserve:
If a reserve applies, ask how much is held back and what the written agreement says about how it is handled after the customer pays.
7) Transfer or delivery charges:
Ask whether any charge applies to receive funds and whether your bank may charge a receiving fee.
8) Minimums or commitment fees:
Ask if you pay a fee when you don’t factor enough in a slow month.
9) What other fees do you charge?
Ask for a full list: setup, portal, monthly fees, invoice fees, due diligence, termination, buyout or anything that can show up later.
10) Contract term:
Ask how long you’re agreeing to, and how it renews.
• Initial term length:
• Renewal term length:
11) What notice do you need to stop factoring?
Ask what “proper notice” means and when it must be given.
• If you’re moving to another factor
• If you just don’t need factoring anymore
If they won’t put it in writing, you can’t really compare it.
Yes. Ask what “non-recourse” actually covers before you compare factoring companies. Some non-recourse programs may protect against customer insolvency or bankruptcy, but may not cover disputes, paperwork problems, short-pays, chargebacks, or customer disagreements.
The safest question is simple: if my customer does not pay, what happens next, and when would I still be responsible?
Yes. You choose which invoices to sell. Most clients start with one customer and one invoice, like a completed load, approved staffing invoice, or manufacturing invoice with backup paperwork. You do not have to factor every invoice just to see whether the numbers work.
Most of our clients are trucking companies, staffing firms, and manufacturers. But we have funded companies across more than 50 industries.
The process works the same for any business that bills other businesses. However, we don't fund most types of construction, third party medical receivables or consumer invoices.
No. Trucking, staffing, and manufacturing are our biggest groups, but we also help many other B2B companies, including:
Plus other businesses that invoice customers on 30–75 day terms.
No. Orange Commercial Credit serves businesses in Nashville, Middle Tennessee, across Tennessee, and throughout the United States.
A factoring company does not need a Nashville office to factor approved invoices for a Nashville business.
The review starts with one customer, one invoice, and the backup paperwork tied to the completed work. If your customer can be approved and the invoice can be verified, we can review the factoring numbers with you.
Yes. We provide freight factoring for Nashville and Tennessee carriers when the broker, shipper, or commercial customer is approved, the freight invoice is verified, and the paperwork supports the delivered load.
That may include the rate confirmation, bill of lading or POD, invoice, paperwork for extra charges such as lumper fees or detention, airport cargo paperwork, or other freight support tied to the completed load.
Once the broker or customer is approved, the invoice is verified, and the account is set up, we usually send most of the money within 24 hours. Nashville carriers can start with one customer and one freight invoice to see the advance, fee, any reserve, payment instructions, and funding timing in writing.
Yes. Those services can matter, but they should not replace the factoring review. Ask whether the broker or shipper can be approved, whether the load paperwork supports the invoice, and whether the advance, reserve, fee, payment instructions, and funding timing are shown in writing.
If a factoring offer includes a fuel card, fuel bundle, mobile app, load board, dispatch service, or other carrier tool, ask whether that extra service changes the fee, minimums, invoice choice, agreement terms, switching terms, or who answers after setup.
Orange Commercial Credit starts with the invoice itself: one broker or shipper, one freight invoice, and the paperwork tied to the delivered load. That may include the rate confirmation, bill of lading or POD, invoice, and paperwork for extra charges such as lumper fees or detention.
Yes, through invoice factoring. Orange Commercial Credit is not a payroll processor, PEO, or short-term payroll lender. We buy approved unpaid B2B invoices so Nashville staffing, logistics, warehouse, industrial, healthcare support, office, and service companies can have money for payroll before customers pay.
The review starts with one customer, one invoice packet, and the backup paperwork tied to the completed work. For Nashville staffing companies, that usually means approved timesheets, the invoice, and the service agreement or customer approval needed to verify the work.
Once the customer is approved, the invoice is verified, and the account is set up, we usually send most of the money within 24 hours. Staffing and manufacturing advances can be as high as 90%.
Yes. We provide manufacturing invoice factoring for Nashville and Tennessee manufacturers, plant suppliers, warehouse suppliers, industrial service companies, parts suppliers, fabricators, machine shops, and other B2B companies when the customer is approved and the invoice can be verified.
Backup paperwork may include a purchase order, bill of lading, packing list, delivery proof, signed QC paperwork, work ticket, vendor approval, or other support tied to completed work.
Once the customer is approved, the invoice is verified, and the account is set up, we usually send most of the money within 24 hours. Staffing and manufacturing advances can be as high as 90%.
Orange Commercial Credit is a national independent direct factoring company serving Nashville, Middle Tennessee, and Tennessee businesses without requiring an office visit.
We fit when a Nashville business wants to compare one customer, one invoice, the backup paperwork, and written terms before deciding. The written quote should show the advance, reserve, fee, payment instructions, funding timing, agreement terms, invoice choice, and who answers after setup.
Yes. Orange Commercial Credit is a national independent direct factoring company serving Nashville, Middle Tennessee, and Tennessee businesses without requiring an office visit.
We review the customer, invoice, and backup paperwork, send the advance after approval and verification, receive the customer’s payment, and service the account after setup.
No. Orange Commercial Credit serves Nashville businesses without requiring an office visit.
A factoring company does not need a Nashville office to factor approved invoices for a Nashville business.
The review starts with one customer, one invoice, and the backup paperwork tied to the completed work.
Customer approval is based on commercial credit review and payment-history information, not on whether the factoring company has an office in Nashville.
Before you decide, we show the advance, reserve, fee, payment instructions, and funding timing in writing.
No. You do not need a factoring company with a Nashville office to review your customer, invoice, and paperwork.
A factoring company does not need a Nashville office to factor approved invoices for a Nashville business.
Customer approval is based on commercial credit review and payment-history information, not on whether the factoring company has an office in Nashville.
Compare the written advance, reserve, fee, paperwork needed, payment instructions, funding timing, agreement terms, invoice choice, and who answers after setup.
Start with the numbers and the service behind them. Ask each factoring company to show the advance, any reserve, the fee, the paperwork needed, funding timing, agreement length, minimums, and who answers after the invoice funds.
The useful comparison is the company that lets you see those details before you decide.
A broker, marketplace, or referral listing may help you collect names. The next question is who actually funds the invoice and services the account.
Before you choose, ask who reviews the customer, who verifies the invoice, what the written agreement says about customer contact, who answers after setup, and who puts the advance, reserve, fee, payment instructions, and timing in writing.
Orange Commercial Credit is a national independent direct factoring company. One customer and one invoice are enough to start the review and see whether the written numbers work.
Nashville searches can mix several business-finance categories. You may see freight factoring firms, transportation-management companies, entertainment business-management firms, risk-management companies, software companies, commercial lenders, broker listings, and national factoring companies serving Nashville.
That does not mean every result is an invoice factoring company. Compare what the quote shows: the advance, any reserve, fee, paperwork needed, payment instructions, funding timing, agreement terms, invoice choice, and who answers after setup.
Compare what the quote shows first. A local office is not needed to factor approved invoices. What matters is who reviews the customer, verifies the invoice, sends the advance, and answers after setup.
A factoring company does not need a Nashville office to factor approved invoices for a Nashville business.
No. Entertainment business management may help artists, musicians, venues, touring companies, or entertainment businesses with reporting, payments, taxes, royalties, budgeting, or financial administration.
Invoice factoring starts with completed B2B work, an invoice, the customer, and the backup paperwork tied to that completed work. If a Nashville entertainment vendor invoices commercial customers on terms, that invoice may be reviewed like other B2B invoices.
Not always. Some freight companies offer quick-pay programs, brokered freight services, logistics support, or freight-management tools. Freight factoring means a carrier sells an approved freight invoice to a factoring company instead of waiting for the broker, shipper, or customer to pay.
Before you choose, ask whether the provider is buying the freight invoice, managing freight, brokering loads, offering quick pay, or providing another service with different costs and responsibilities.
Ask what has to happen before funding. A 3–5 day setup claim, quick-pay claim, no-upfront-fee wording, or fast-approval wording may still depend on customer approval, invoice verification, account setup, required backup, and signed agreement terms.
Also ask which charges, minimums, dispute or short-pay terms, termination terms, portal terms, or other conditions are shown before you sign.
A broker, marketplace, or referral listing may help you collect names. The next question is who actually funds the invoice and services the account.
Before you choose, ask who reviews the customer, who verifies the invoice, what the written agreement says about customer contact, who answers after setup, and who puts the advance, any reserve, fee, payment instructions, and timing in writing.
Orange Commercial Credit is a national independent direct factoring company. One customer and one invoice are enough to start the review and see whether the numbers work.
The written quote and agreement should explain what your customer sees, where payment is sent, and any verification steps tied to the invoice.
The work you completed and the invoice amount do not change because the invoice is factored. Ask for the payment instructions and customer-contact process in writing before you decide.
Receivables factoring, accounts receivable factoring, and invoice factoring usually refer to selling approved invoices. “A/R financing” or “A/R funding” can also refer to lending against receivables, so ask whether the provider buys the invoice or lends against it.
But it’s not on you.
We get it.
There’s no setup fee just to review the opportunity. We’ll explain what we need, what can be reviewed, and the next step before you decide.
If the proposal looks right to you, we’ll set up an agreement. It’s a 90-day factoring agreement with no minimum number of invoices required.
If the account is approved and set up, you choose when to factor an approved invoice.
The agreement lays out the basics:
After account setup, customer approval, invoice verification, and required backup, we usually send the advance within 24 hours.
A staffing owner put it this way:
“I can always count on them to send me funds when I need it.”
—George, Owner and Client Since 2016, Staffing Company, KY
No minimum invoice count. You decide when to use it.
You also get a dedicated account executive who knows your business and picks up when you call — answering your questions on the spot.
And you can log in any time day or night to check on balances and invoices.
If it makes sense, great. If not, you’ll still leave knowing more than you did before.
And for the owners who don't put it off,
here’s what it looks like.
An intermodal owner told us what makes it work:
“We submit our invoices almost daily using their scanning program, and know that when we submit before the deadline we get same day funding.”
—Mike, President Intermodal Transportation & Warehousing Company, and Client Since 2006
After account setup, customer approval, invoice verification, and required backup, we usually send the advance within 24 hours. Payroll, fuel, and shop bills can then be covered without waiting out the customer’s terms.
That’s why we show the numbers in writing before you decide.
Most owners start with just one invoice — enough to see how the numbers work.
In the end it always comes
back to the same thing:
one customer,
one invoice,
one call.
For a real conversation:
1-800-231-3878
Independent and privately held
since 1979.
No setup fee, no minimum invoice count, and you talk to a person who knows your account.
🌙
After hours? No problem.
After hours, or if you’d rather not call, fill out this form and we’ll call you back.
Related invoice factoring pages for Nashville and Tennessee companies