“You should talk to these guys.”
Serving Clients Nationwide Since 1979
Invoice factoring for North Charleston, Charleston County, the Lowcountry, and South Carolina businesses that bill B2B customers on terms.
(also called accounts receivable factoring or receivables factoring)
Orange Commercial Credit is an independent, privately held nationwide direct factoring company. We work directly with North Charleston and South Carolina businesses that bill other businesses on terms.
We buy approved unpaid invoices for trucking, staffing, manufacturing, and other B2B companies so you can get paid before your customer’s 30, 60, or 75-day terms end.
After account setup, customer approval, invoice verification, and required backup, we usually send the advance within 24 hours.
Before you decide, we show the numbers in writing: the advance, any reserve, the fee, and funding timing.
A factoring company buys approved unpaid B2B invoices so a business can get paid before its customer pays on terms.
When you search for North Charleston factoring companies, the results can answer two different questions: Which companies have an office in or near North Charleston? And which factoring companies serve North Charleston businesses?
A map helps answer the first question. It shows nearby locations. It does not show every factoring option available to a North Charleston business.
So before you narrow the comparison to nearby offices, it helps to know whether a North Charleston office is actually necessary.
No. A factoring company does not need a North Charleston office to factor approved invoices for a North Charleston business. If meeting in person matters to you, a local office gives you that option.
The review itself centers on the customer and the work behind the invoice. Customer approval starts with commercial credit review and payment-history information. At Orange Commercial Credit, our credit managers use national commercial credit databases to review your customer. We also verify the invoice and the backup paperwork tied to the completed work. None of those steps requires a North Charleston office.
Invoice factoring for North Charleston, Charleston County, the Lowcountry, and South Carolina businesses that bill B2B customers on terms.
North Charleston search results can include North Charleston and Charleston-area factoring pages, statewide South Carolina factoring pages, national direct factoring companies, brokers, ranking sites, industry specialists, and finance companies that offer a different product.
Those results do not all represent the same kind of provider. Compare who buys the invoice directly, which industries the company specializes in, and who answers your questions after setup.
Orange Commercial Credit buys approved invoices directly. We specialize in trucking and freight, staffing companies that need payroll funding, and manufacturers. We also review approved invoices from other B2B businesses, including logistics, warehouse, port and maritime support, aerospace suppliers, automotive suppliers, industrial services, and distribution. After setup, you work with a dedicated account executive backed by an experienced team. One customer and one invoice can start the review.
You may have heard about us from a friend, or you may be comparing North Charleston factoring companies after a search. However you got here, the pressure is usually the same.
You need the money before your customer pays on
30, 60, or 75-day terms.
The work’s already done. The invoices are out. And your bills are piling up while you are left waiting.
Trucking. Staffing. Manufacturing.
Different work. Same wait.
Your customer wants 30, 45, or even 60-day terms. To win the business, you agree. No matter the terms, you still have bills to pay.
Payroll, fuel, insurance,
materials, equipment, repairs...
The bills keep coming while you wait out those terms. You can put expenses on a card while you wait, but the card bill comes due long before your customer pays.
Wait too long and you’re the one
stuck with late fees or interest.
That pressure is why the lowest advertised rate is not enough. Before you choose, compare what each company will put in writing for one real customer and one real invoice.
North Charleston search results can mix local office pages, national direct factoring companies, freight and staffing specialists, brokers or matching services, ranking pages, and commercial-finance companies offering a different product.
Headlines may mention same-day or 24-hour funding, high advance rates, low-rate wording, recourse or non-recourse programs, fuel or carrier tools, local service, or national access. Those claims do not all describe the same product or the same point in the review.
Those offers do not all describe the same product or the same stage of approval or funding. Before comparing rates, identify who funds the invoice and what the written quote says for your customer and invoice.
Healthcare staffing invoices and third-party medical receivables are different categories. Orange Commercial Credit generally excludes third-party medical receivables.
After you confirm the industry fit, compare the complete written cost, not only the lowest advertised rate. Ask what invoice volume, customer-payment timing, minimums, and other charges the rate assumes.
The written numbers are what let you compare the quote without guessing.
With Orange Commercial Credit, you won’t have to chase three people to find out what’s happening with your invoice. After setup, you work with a dedicated account executive who knows your business and paperwork, backed by an experienced team.
One freight carrier described that account relationship this way:
“She has been a vital part of our ability to navigate our freight business, and is always there when we need her.”
—freight carrier client for several years
One transportation client described that account relationship this way:
“We have daily email contact with April and she’s so responsive to our needs.”
—Jennifer, Manager and OCC Client Since 2014
Account support is one part of the comparison. Use the table below to check the claims you see in search against the written quote before you decide.
| What you see in search | What to check before you choose |
|---|---|
| North Charleston office, nearby Charleston-area office, or local-presence wording | Whether the location is a real operating office, the legal company name, who funds the invoice, whose agreement you sign, who services the account, and what the written quote shows. |
| Map listing, local phone number, reviews, or ratings | What the listing actually proves about the provider, whether the company directly factors invoices, and what written terms apply to your customer and invoice. |
| High advance rate | What advance your customer and invoice qualify for, whether a reserve applies, what fee applies, and whether the number is an advertised maximum. |
| Large credit line or funding-capacity claim | Which product the limit applies to, whether it is the account facility or the advance on one invoice, and what other terms or collateral apply. |
| Fast approval or quick digital approval | Whether the timing refers to an application response, customer review, account setup, or approval of a specific invoice. |
| Same-day funding wording | Whether the claim applies after account setup, customer approval, invoice verification, and required backup, and what the written quote says for your invoice. |
| 24-hour or 24-to-48-hour funding wording | Which step the timing describes and what must be completed before the provider sends the advance. |
| Low fee, transparent rate, or “no hidden fee” wording | How the fee is calculated, what payment period or volume the example assumes, and what other charges are listed in writing. |
| No setup fee, no upfront fee, or no application fee wording | Which charge is actually waived and whether any other account, transfer, portal, documentation, or due-diligence charge is listed in writing. |
| Spot or selective factoring wording | Whether you choose which approved invoices to submit and whether the agreement places any limits on invoice choice. |
| No-minimum wording | Whether the claim means no minimum invoice count, no minimum monthly dollar volume, no minimum fee, or something else. |
| No long-term contract or short-agreement wording | How long the agreement runs, what the written agreement says about ending it, and how open invoices are treated. |
| Recourse or non-recourse factoring wording | What type of customer nonpayment the written agreement covers, what is excluded, and what it says about a dispute or short pay. |
| Fuel card or fuel-bundle offer | Whether the broker or shipper can be approved, whether the load paperwork supports the invoice, and whether the added service changes the written fee, minimums, invoice choice, or agreement terms. |
| Mobile app, portal, or online invoice tools | What can actually be submitted or reviewed online, what the portal shows, and whether a person answers after setup. |
| Customer or broker credit-check feature | What commercial-credit and payment-history information is reviewed and whether approval of the customer and invoice is still required. |
| Customer-contact or payment-instruction language | Where the customer sends payment, what the written agreement says about payment instructions, and who answers invoice or payment questions. |
| Freight, trucking, drayage, or intermodal specialization | Whether the broker or shipper can be approved and whether the rate confirmation, bill of lading, POD, intermodal paperwork, and other load backup support the invoice. |
| Staffing factoring or payroll funding | Whether the offer is invoice factoring, payroll processing, back-office administration, or another product, and what approved timesheets and service documentation are required. |
| Manufacturing, warehouse, industrial, or another commercial-finance offer | Whether the provider is buying an approved invoice for completed B2B work or offering a different product tied to receivables, equipment, inventory, purchase orders, or other assets. |
| Business size and monthly invoice volume | ask whether the provider works with small businesses, midsize companies, or larger accounts, whether it has a minimum or maximum monthly invoice volume, and whether pricing or commitment fees change as volume changes. |
| Account support | after setup, you work with a dedicated account executive backed by an experienced team. |
Search can group together North Charleston and Charleston-area factoring pages, statewide South Carolina factoring pages, national direct factoring companies, brokers, ranking sites, industry specialists, and finance companies that offer a different product.
The table below separates those roles so you can verify who reviews the customer and invoice, whose agreement you sign, who funds the invoice, who services the account, and what the written quote shows.
| Provider or listing type | What it usually means | What to check before you choose |
|---|---|---|
| North Charleston or Charleston-area factoring page | May show a North Charleston-specific page, a Charleston-area service page, a local phone number, reviews, ratings, industry claims, or Charleston-specific factoring terms. | The legal company name, who actually funds the invoice, whose agreement you sign, who services the account, and what the written quote shows. |
| Statewide South Carolina factoring page | May describe service across South Carolina, list several industries, and present statewide funding, approval, advance-rate, or qualification claims without a North Charleston office. | Whether the provider directly reviews and funds your invoice, what customer and paperwork requirements apply, whose agreement you sign, and who answers after setup. |
| National ranking list or review site | May compare large factoring companies by advance rate, fees, funding speed, industry fit, software integration, recourse terms, or general qualification requirements. | Whether the listed company fits your actual customer, invoice, paperwork, agreement terms, minimums, any reserve, customer payment instructions, and account-support needs. |
| Broker, marketplace, or advisory service | May collect your quote request and pass your information to one or more factoring companies instead of reviewing, funding, and servicing the account directly. | Which company actually reviews the account, provides the quote, funds the invoices, and services the account; whose agreement you sign; and how the intermediary is paid. |
| National independent direct factoring company serving North Charleston | Reviews the customer and invoice, factors approved invoices, sends the advance, receives the customer’s payment, and services the account without requiring a North Charleston office visit. | Whether one customer and one invoice are enough to start and whether the written quote shows the advance, any reserve, fee, payment instructions, funding timing, agreement terms, invoice choice, and account support. |
| Freight or trucking factoring provider | Usually focuses on carriers, brokers, shippers, rate confirmations, PODs, bills of lading, port freight, drayage paperwork, intermodal paperwork, ro-ro freight, fuel-related services, mobile apps, load boards, or other carrier tools. | Whether the broker or shipper can be approved, whether the load paperwork supports the invoice, and whether extra services change the fee, minimums, invoice choice, agreement terms, switching terms, or account support. |
| Staffing factoring company or payroll funding provider | May focus on staffing invoices, approved timesheets, weekly payroll, payroll processing, back-office support, tax filing, onboarding tools, or timekeeping software. | Whether the service is invoice factoring, payroll processing, back-office administration, or another product with different costs and responsibilities. |
| Software-connected or accounting-platform factoring company | May connect with accounting software or online invoice tools and focus on application flow, invoice submission, or platform integration. | Whether the customer can be approved, the invoice can be verified, the fee is clear, any reserve is explained, and a person can answer after setup. |
| Technology, IT, office-service, or commercial-service factoring provider | May focus on B2B service companies, IT staffing, technology vendors, office-service companies, port-support companies, industrial service companies, or commercial service businesses with customer contracts and recurring invoices. | Whether the customer can be approved, whether the service invoice can be verified, and whether the service agreement, purchase order, work ticket, or customer approval supports the invoice. |
| Construction, contractor, medical receivables, consumer-finance, equipment-finance, or purchase-order funding provider | May offer invoice factoring, but may also offer a different finance product or work with a different type of receivable. | Whether the offer buys approved unpaid B2B invoices for completed work or uses different collateral, repayment, reporting, customer-notice, and exit terms. |
| Bank-backed, secured-loan, asset-based, or commercial-finance provider | May offer invoice factoring, asset-based lending, secured loans, equipment finance, inventory finance, purchase-order funding, or another working-capital product. | Whether the offer buys approved invoices or creates a different financing obligation with separate collateral, repayment, reporting, customer-notice, and exit terms. |
Orange Commercial Credit is a national independent direct factoring company serving North Charleston and South Carolina businesses.
Here is what that means for the invoice you want to factor.
The details matter because the rate alone does not tell you what happens before funding or after your customer pays. A written quote should show the customer review, invoice review, advance, any reserve, fee, payment instructions, funding timing, agreement terms, invoice choice, and account support.
At Orange Commercial Credit, we buy approved invoices for work you’ve already done. We’ve provided invoice factoring since 1979.
Through recessions, slow seasons, and the ups and downs of every business cycle, Orange Commercial Credit has kept clients funded so payroll, fuel, and repairs get paid even when your customers’ payments are still weeks away.
You send us your customer's invoice and once it's approved, we send you most of the money up front.
This up-front payment is called an advance. Depending on your industry, it can be as high as 98% of the invoice.
When your customer’s payment posts to our bank, any available reserve releases under the written agreement terms, minus the factoring discount fee, which can range from 1.25% - 5%.
You choose which invoices to sell. Use it when you need it, skip it when you don’t.
We’ve been through decades of change, but one thing never changes: your bills don’t stop. That’s why your money shouldn’t wait.
Over the years we’ve worked with trucking companies, staffing firms, service providers and manufacturers just like you. Many have been with us five years or more.
They stay because the money’s there when they need it and because they value the service they receive.
They have one dedicated account executive who is backed by an experienced team ready to answer all their questions.
Most of our business comes from referrals. Our clients refer because they know their friends will get the same service they do.
A produce hauler told us what it feels like working with OCC:
“We love OCC! They have taken care of us since 2021. We have the pleasure of working with our account rep. She is such a big help. Always quick to respond to any questions or inquiries we may have. She is always available and I know that I can always count on her. She’s the best! Quick payment, great rates, excellent communication. A trusted company. Highly recommend.”
—Mariya, Owner-Operator, Produce Hauler
A trucking owner told us how she first came to OCC:
“I turned to my friend Mike for advice and he referred me to his factor… OCC. She reviewed my paperwork and explained step by step what I needed to do including outlining who to contact, what numbers to reference and what I needed to ask.”
—Alyssa, Owner, Long-Haul Trucking Company
With us, even if your customer pays on 30, 45, or 60-day terms, you’ll have the cash in your account; usually within 24 hours of invoice approval once you’re established as a client.
Trucking, staffing, and manufacturing companies in
North Charleston and across South Carolina use us when the wait gets too long.
One customer. One invoice. One call.
Call with one customer name and one invoice in mind. We’ll tell you what paperwork we need, review whether the customer can be approved, and show the advance, fee, any reserve, and timing before you decide.
You get a person, not a menu:
1-800-231-3878
The only way this works is if your customer’s good for it. That’s why our credit check matters.
We’ve been doing this since 1979, and many of our credit team members have been here 10+ years. They know how to check credit right.
We focus on getting you paid faster on approved invoices.
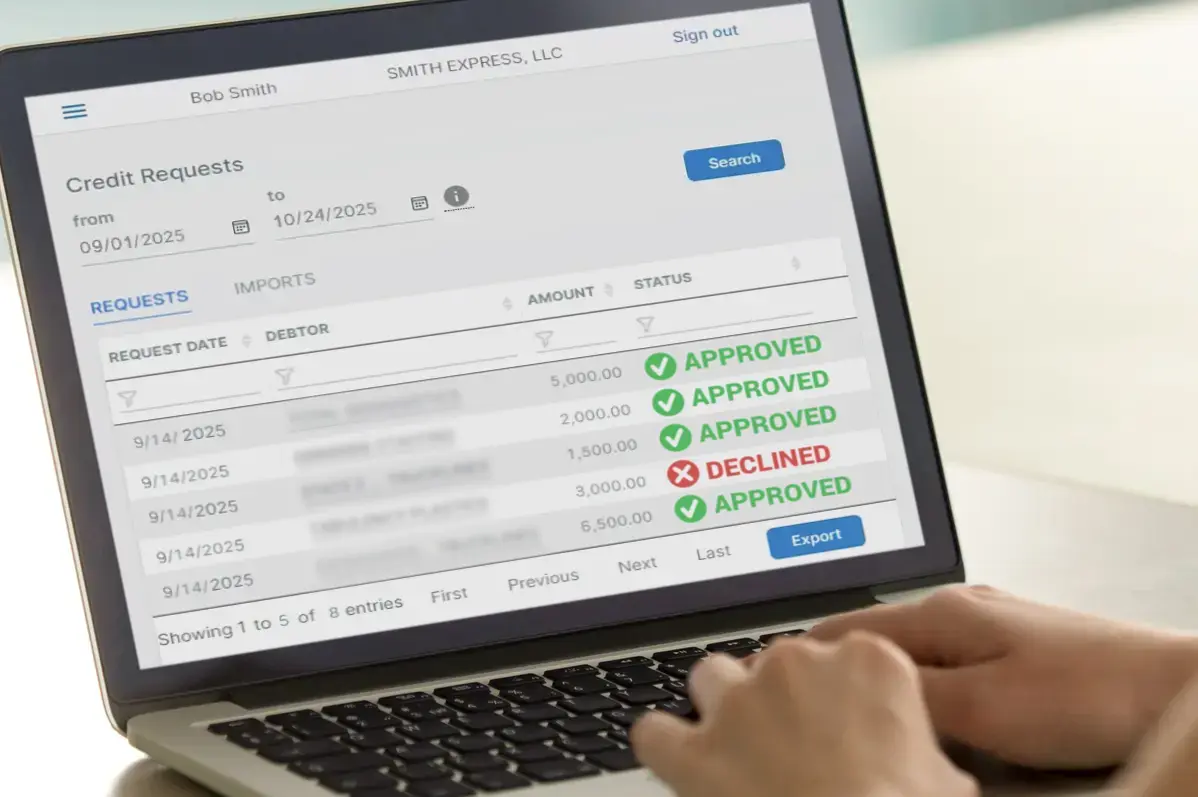
It’s one thing to hear you’ll get paid...
Here’s what happens, step by step, from the time you send an invoice until the final payment clears.

In invoice factoring, the first thing we do is check your customer’s credit. We pull their payment history up front, even before you send us an invoice, because that’s how we decide if we can buy the invoice from you.

Once they're approved, you send an invoice, and our team then reviews the supporting paperwork that goes with it.
Once your customer is approved, the invoice is verified, and your account is set up, the written payment instructions show where your customer sends payment.
The work you did and the price on the invoice stay the same.

The last step is the advance, the part you care about most.
That’s when we send the advance.
On every funding you’ll see:
For some industries, we can advance up to 98% of the invoice within 24 hours. On a $10,000 trucking company invoice, that usually means $9,700 to $9,800 up front.
If a reserve applies, it is the portion of the invoice not included in the advance. Your written numbers should show whether there is a reserve and how it is treated under the agreement.
When your customer’s payment posts to our bank, any available reserve releases under the written agreement terms, minus the fee.
The discount fee depends on:
Whatever the case, we let you know the fee before you decide. No surprises.
That's how our factoring works.
Ready to see your numbers? You see the advance, any reserve, and our fee before you decide. Call and we’ll walk through one invoice on the phone:
1-800-231-3878
The difference with us? We’re independent so we can set your terms the way you need them.
We don’t answer to outside investors. We’re privately held with no board calling the shots. We’re business owners too.
Your terms come from us, and no one else.
We know what it takes to meet payroll and keep the lights on. And we also know that every business is different. We don't drop numbers into a formula.
We base terms on what we see in your invoices and your customers, not on a one-size-fits-all chart.
One flatbed hauler said it best:
“It doesn’t matter if you bring $1 or a million, I guarantee you these people will treat you as a family member. We will always see these people as a great place for financial support and great customer care.”
—Rico, Flatbed Hauling
In the end, it comes down to trust. Who do you want to rely on when the bills can’t wait? With us, it starts simple: pick one customer, one invoice, and make one call.
You’re probably asking: So how would this work in my business?
The answer depends on the work you do.
We don’t fund most types of construction, third party medical receivables or consumer invoices. But we have funded companies across more than 50 industries.
We fund invoices for work that’s already done. The goods are already delivered, but your customer’s on terms.
The real issue is when the wait drags well beyond 30 or 45 days.
Let's walk through a few examples in trucking, staffing, and manufacturing, the industries where this matters the most.
Trucking advances can be as high as 98% of the invoice.
Orange Commercial Credit provides freight factoring for carriers that have delivered the load and invoiced a broker, shipper, or other B2B customer. We buy approved freight invoices so carriers can have money for fuel, repairs, payroll, and other bills before the broker or shipper pays. Freight factoring is also called trucking factoring.
Trucking companies are Orange Commercial Credit’s largest client group. For North Charleston, Charleston County, the Lowcountry, and South Carolina carriers, our team reviews broker credit and the invoice packet: signed rate confirmation, bill of lading or POD, invoice, and paperwork for extra charges such as lumper fees or detention.
If you are comparing trucking factoring companies or freight factoring companies, a fast-funding claim, fuel-card offer, app, load-board integration, or 24/7 funding headline does not show the full quote. Start with one broker or shipper, one delivered load, and the paperwork tied to that load.
The quote should show the advance, reserve, fee, funding timing, agreement terms, invoice choice, customer payment instructions, and who answers after setup.
North Charleston freight can touch the North Charleston Terminal, Hugh K. Leatherman Terminal, Navy Base Intermodal Facility, I-26, I-526, Remount Road, North Rhett Avenue, Palmetto Commerce Parkway, nearby rail connections, and chassis pools. The useful question is whether the customer and completed-load paperwork can be reviewed before the next fuel, payroll, or repair bill comes due.
Ask whether the broker or shipper can be approved before you haul, what paperwork is needed after delivery, when the advance can go out, and how the reserve releases after the customer pays.
Also ask whether the factoring offer includes recourse terms, non-recourse wording, monthly minimums, invoice-submission fees, ACH or wire fees, app or portal fees, fuel-card terms, fuel-bundle terms, or switching terms.
If a factoring offer includes a fuel card, fuel bundle, mobile app, load board, dispatch service, 24/7 funding, or other carrier tool, ask whether that extra service changes the fee, minimums, invoice choice, agreement terms, switching terms, or who answers after setup.
The written numbers are what let you compare the quote without guessing.
Orange Commercial Credit factors approved invoices for carriers hauling many different types of freight. The paperwork can vary from one load to the next, depending on the customer, what was delivered, and any added charges.
Local and regional carriers may haul palletized freight, make multiple stops, or work with tighter delivery windows. Delivery records should show what was delivered and that the load was completed.
For full truckload freight moving between markets, common backup may include the rate confirmation, bill of lading, proof of delivery, and documents for any added charges.
Less-than-truckload and multi-stop freight can create more delivery records because one load may involve several stops. The required backup can vary by customer and invoice.
Temperature-sensitive loads may add temperature records, delivery documents, lumper receipts, detention approval, or other backup for added charges.
Specialized loads may require routing, permit, inspection, delivery, or added-charge documents in addition to proof of delivery.
Scale tickets, delivery tickets, job records, or other load-specific documents may support the invoice.
Bulk freight may rely on meter tickets, scale tickets, bills of lading, delivery records, or other documents showing what was delivered and accepted.
Hot shot and expedited freight still needs delivery records and any customer-specific backup required for the invoice.
Ask whether the broker or shipper can be approved before you haul, what paperwork is needed after delivery, when the advance can be sent, and what the written agreement says about any reserve after the customer pays.
Intermodal loads can require a combination of interchanges, delivery orders, J1s. They can also require work orders, bills of lading, and a proof of delivery.
We work with all of them every day
and the story's always the same.
The load’s already hauled. The paperwork’s in. The only thing missing is the money in your account.
And the paperwork looks different depending on the job.
However you haul it, the wait is the same.
The load’s delivered, the paperwork’s in, and you’re still not paid.
Meanwhile, fuel, payroll, and repairs are due now. That’s when you sell us the invoice, and we send the cash.
You’ve seen the ads: same-day funding, fuel cards, mobile apps, even 24/7 payouts. That’s all fine.
So the real question is:
Will the money actually
be there when you need it?
After account setup, customer approval, invoice verification, and required backup, we usually send the advance within 24 hours.
And what about brokers?
You may not know if one’s been paying slow before you book the load.
That’s what our credit team does every day. We flag slow payers before you haul, so you don’t waste miles on a load that won’t pay.
We’ve been doing this since 1979. Many on our credit team have been here more than ten years.
That experience helps the team review the customer, invoice, and paperwork tied to the completed load.
Friday payroll comes due. Fuel card drafts this week. The truck note hits this month.
And the shop won’t release a truck until the repair’s paid. Plus, you need tires and have insurance renewals.
Carry a balance on your card, and the interest adds up.
Fuel bills spike, and drafts hit your account whether or not a broker’s check has cleared.
None of those bills wait.
You need to get paid.
If you run freight through North Charleston, the day can turn on the North Charleston Terminal, Remount Road, I-26 exit 212C, I-526 East, North Rhett Avenue, the Hugh K. Leatherman Terminal, the Navy Base Intermodal Facility, Drayage Road Bridge, Palmetto Railways switching, CSX, Norfolk Southern, SMART Pool chassis, and customer delivery windows.
Around Remount Road, Virginia Avenue, Ashley Phosphate Road, Palmetto Commerce Parkway, West Aviation Avenue, Pierside Street, the Don Holt Bridge, and the I-526 Lowcountry Corridor WEST construction zone, drayage, ro-ro automotive freight, intermodal containers, flatbed loads, auto-hauler moves, warehouse overflow, and over-dimensional freight can all depend on the same ramps, crossings, bridges, gates, and chassis pool.
At the North Charleston Terminal, cargo access can run through I-26, I-526, North Rhett Avenue, Remount Road, rail switching, chassis return rules, and terminal gate timing before the truck reaches the next move. On West Aviation Avenue, freight rail crossings can back up traffic into I-26 congestion before a truck reaches a warehouse, rail yard, or terminal gate.
When one I-526 slowdown, Ashley Phosphate merge delay, Remount Road ro-ro move, SMART Pool chassis issue, West Aviation Avenue rail crossing, Drayage Road Bridge handoff, or over-dimensional routing limit runs late, the delivery window gets tighter and the next load starts late.
If the delivery window closes, the load waits.
You still have fuel to buy.
Payroll is Friday. Your customer may still be paying on 30, 60, or 75 day terms.
A fleet owner put it this way:
“Amazing people working at this company! Always a phone call away always eager to help and always getting the issues solved. Great % rates and overall great people starting from managers to accountants and assistants. Been working with them for over 4.5 years with no problems or complications what so ever.”
—Vitaliy, Interstate Freight Carrier
An intermodal freight fleet owner told us what OCC meant for his business:
“Orange Commercial Credit (OCC) was instrumental in our growth from the very beginning. They not only understand the trucking industry but also specialize in the intermodal and drayage business. The funding is quick, the relationships are deep, the rates are fantastic, and the trust earned is invaluable. I have been able to personally recommend OCC to many of our Clients over the past years and have always heard great feedback in return. Thank you OCC for your commitment and friendship. Clients like me really do appreciate it!”
—Michael S., President, Intermodal, Client since 2013
A long-haul carrier told us why the credit check matters:
“OCC is an exceptional factoring company! Not only do they help us with our invoices, but also advise us on broker credibility, ensuring that we are getting paid for our work. I would like to express my sincere appreciation to my AE for her prompt responses to my inquiries. It makes a real difference.”
—Tom A., Long-Haul Trucking
Tom’s quote shows what a fleet counts on with credit checks. But when it’s just you and your truck, it’s fuel, repairs, insurance, and the bills waiting at home. All on you.
Fuel card drafts hit every week. The truck note’s coming due. Add shop repairs and home bills. Waiting 30–45 days for a broker to pay just doesn’t cut it.
That’s why we usually send the money within 24 hours; so it’s there before the next bill hits.
Here’s how another owner-operator put it after using OCC for years:
“I'm a small carrier owner operator.
I've been using Orange Commercial Credit for about 4 years now and I couldn't be more happier with the service provided by OCC.
OCC is very fair with their rate and they pay out very quickly (next day).
Their staff is great, very professional and nice.
I recommend OCC for all carriers who need a factoring company.”
—Ezechiel, Owner-Operator, OCC client since their first load
Ezechiel’s an owner-operator, and the bills don’t wait any less when you’re hauling hot shot loads.
Hot shot runs are smaller, but the bills still stack up just as fast.
Whether you're in an F-350, a Ram, or a Duramax with a gooseneck or bumper-pull, one stretch of repair and fuel bills can drain your cash fast.
You could really use that new Big Tex tandem dual wheel, but trailer payments stack up fast.
And if a broker’s been paying slow, you hear it from us before you waste the trip, not later.
A hot shot driver explained why she sticks with OCC:
“Orange Commercial Credit is an excellent company to work with. They offer exactly what we need to run our trucking company, we always know what brokers are safe to work with due to Orange’s credit check feature. Staff is always friendly and helpful. I have never had a bad experience with our assigned Account Executive or any other staff member for that matter, the whole team is great!”
—Crystal, Hot Shot Trucking
You’ve done the work. You shouldn’t be waiting a month to see the money.
Most clients start with just one customer, one invoice, and one call to us. Even if you just have a question, call us. We'd be happy to talk with you.
If you’re running loads in or out of North Charleston or anywhere in South Carolina, we can walk through one invoice on the phone: 1-800-231-3878
We’ve been checking broker and shipper credit since 1979.
Staffing advances can be as high as 90% of the invoice.
Orange Commercial Credit provides payroll funding for staffing companies through invoice factoring. We buy approved unpaid B2B invoices so staffing agencies can have money for payroll before customers pay.
If you are comparing staffing factoring companies or payroll funding companies, start with one customer, one invoice, approved timesheets, the service agreement or customer approval, and the written quote.
North Charleston staffing firms may be filling warehouse, logistics, port-support, aerospace, automotive, manufacturing, healthcare-support, federal-contractor, technical, and light-industrial shifts while customers stay on 30, 60, or 75-day terms.
Once the customer is approved, the invoice and timesheets are verified, and the account is set up, we usually send most of the money within 24 hours so payroll can stay on schedule.
If you run a staffing agency, payroll means two things: the recruiters in your office and the workers already out on site.
Timesheets get signed, checks go out every Friday, and customers may not pay for 30, 60, or more days.
The hours are already worked. Payroll’s due. The money isn’t in yet.
However you staff it, the work is done and you’re still waiting to get paid.
And it’s never just wages. You may also have:
Ask whether the customer can be approved, whether the timesheets support the invoice, when the advance can go out, whether a reserve applies, and how the reserve releases after the customer pays.
Also ask whether the offer includes recourse terms, non-recourse wording, monthly minimums, invoice-submission fees, ACH or wire fees, portal fees, background-check charges, payroll-processing charges, back-office charges, or switching terms.
If a payroll funding offer includes back-office support, payroll processing, tax filing, timekeeping software, onboarding tools, or recruiting support, ask whether that extra service changes the fee, minimums, invoice choice, agreement terms, switching terms, or who answers after setup.
The written numbers are what let you compare the quote without guessing.
Orange Commercial Credit factors approved invoices for staffing companies placing workers in many types of jobs. Payroll may be due while customers are still paying on 30-, 60-, or 75-day terms. The paperwork changes with the assignment. One invoice may rely on approved timesheets, while another may require different time records or backup tied to the work completed.
Production workers, assemblers, packers, machine operators, and other industrial placements can put workers on payroll before the customer pays the staffing invoice.
Pick-pack crews, forklift operators, shipping and receiving workers, inventory teams, and warehouse support staff may work shift after shift while the staffing company pays workers before the customer invoice is paid.
Welders, maintenance technicians, machinists, electricians, mechanics, and other skilled-trades placements may require credentials, site records, and approved time records to support the assignment and invoice.
Nurses, aides, medical assistants, and other healthcare staffing workers may need to be paid on schedule even when the staffing customer pays later. Healthcare staffing invoices are different from third-party medical receivables, which Orange Commercial Credit generally excludes.
Contract IT, network, software, data, and cybersecurity assignments may last for weeks or months, with several payroll periods passing before the customer pays the invoice.
Engineering support, quality, laboratory, technical, and project assignments may involve longer assignments, specialized approvals, and time records that support the invoice.
Around Clements Ferry Road, Palmetto Commerce Parkway, I-26, Camp Hall, Ridgeville, North Charleston, Hanahan, Ladson, West Ashley, Henry Tecklenburg Drive, and the Joint Base Charleston side, a staffing order can require background checks, credentials, VMS entries, reliable transportation, or same-week availability before the worker clocks in.
Administrative support, clerical, call-center, customer-service, and office placements still put workers on payroll before many customer invoices are paid.
Accounting, finance, management, project, and other professional contract roles may continue across multiple payroll periods, with time records and customer invoices generated throughout the assignment.
If your staffing orders run through North Charleston, the week can turn on North Charleston warehouse shifts, Palmetto Commerce Parkway logistics crews, Ridgeville automotive support, Camp Hall manufacturing roles, Hanahan and Ladson light-industrial work, Charleston-area healthcare coverage, cleared logistics roles, and worker start times.
Around Clements Ferry Road, Palmetto Commerce Parkway, I-26, Camp Hall, Ridgeville, North Charleston, Hanahan, Ladson, West Ashley, Henry Tecklenburg Drive, and the Joint Base Charleston side, a staffing order can require background checks, credentials, VMS entries, reliable transportation, or same-week availability before the worker clocks in.
Warehouse, aerospace, automotive, van assembly, packing, forklift, logistics, healthcare, clinical, non-clinical, federal-contractor, technical, manufacturing, and light-industrial roles can all pull from the same North Charleston-area worker list in the same week.
When one worker does not show for the first shift, one credential waits, one background check delays, one VMS entry does not match the timecard, or one I-26 commute does not line up with the start time, the agency still has to fill the shift and run payroll.
If a shift is not filled, the hours are not billed. You still have rent, insurance, payroll taxes, workers’ comp, and recruiter payroll to pay.
North Charleston-area warehouse, logistics, aerospace, automotive, healthcare-support, manufacturing, and light-industrial shifts can all create the same weekly problem:
the work is completed before the customer pays.
Payroll is Friday. Your customer may still be paying on 30, 60, or 75 day terms.
Without funding, some owners try to stretch their own payables or pay bills with credit cards. Others dip into personal savings, just trying to bridge the weeks until customers finally send payment.
A staffing owner explained how OCC let him take on more customers:
“I can always count on them. Orange Commercial has helped me take on clients I normally could not afford to take. The setup process with them was easy. They let you choose which clients you want to factor. Pricing is reasonable for the industry. Customer service is great and I can always count on them to send me funds when I need it.”
—George, Owner and Client Since 2016, Staffing Company
A staffing owner told us how OCC changed his cash flow:
“As a staffing company owner, I heavily rely on cash flow to keep my operations running smoothly and meet payroll, OCC's factoring process is incredibly streamlined and hassle-free. Their newly implemented online platform is user-friendly, making it easy for me to submit and track invoices. This new system allows me to receive funds quickly and efficiently, greatly improving my cash flow management. I highly recommend them.”
—Joe, Owner, Staffing Company,(Client since 2018)
And that’s how factoring works in staffing. A lot of owners call it payroll funding. Payroll runs every week, along with taxes, insurance, and benefits. With Orange Commercial Credit, the funds are there so checks go out on time.
You’ve made payroll. You shouldn’t be carrying it for weeks while customers take their time.
You send the invoice and approved timesheets; we review and send funds so your people get paid on time, even when customers take 30–60 days to pay you.
Most agencies start with one customer, one invoice, and approved timesheets.
We can review the customer, invoice, timesheets, and written numbers before you decide.
We advance on your staffing invoices so you can run payroll,
pay taxes, and cover benefits.
Manufacturing advances can be as high as 90% of the invoice.
For North Charleston manufacturers comparing manufacturing invoice factoring, the comparison should start with the customer, invoice, purchase order, packing list, bill of lading, delivery proof, inspection record, or signed QC paperwork tied to the completed order.
North Charleston and Lowcountry manufacturers may be buying raw materials, paying suppliers, scheduling shop work, shipping finished goods, or waiting on customer payment from aerospace, automotive, port-support, industrial, warehouse, and other commercial accounts. I-26, I-526, port routing, rail timing, warehouse docks, bridge traffic, terminal handoffs, and heavy-haul routing can all affect when raw materials or finished goods reach the next production step.
If a search result mentions purchase order financing, asset-based lending, equipment financing, supply-chain finance, import/export finance, or a line of credit, ask what the money is tied to: a purchase order, finished goods, a verified invoice, equipment, inventory, receivables, or a larger credit facility.
Once the customer is approved, the invoice is verified, and your account is set up, we usually send most of the money within 24 hours so payroll, materials, and supplier bills can stay on schedule.
Staffing firms feel it every Friday. Manufacturers do too, just with different bills.
Yes. Purchase order financing, asset-based lending, equipment financing, supply-chain finance, import/export finance, and invoice factoring can all appear in North Charleston manufacturing search results. The question is what the money is tied to: a purchase order, finished goods, a verified invoice, equipment, inventory, receivables, or a larger credit facility.
Purchase order financing may be reviewed before finished goods are delivered. Asset-based lending or equipment financing may depend on collateral, reporting, and larger credit terms. Invoice factoring starts after work is complete, the customer can be reviewed, and the invoice backup supports the bill.
Before you decide, ask which product is being quoted, what paperwork is needed, where the customer sends payment, and when any reserve can release.
If your manufacturing work runs through North Charleston, the day can turn on the aerospace assembly campus, the new final assembly building, the large-cargo aircraft servicing area, Dorchester Road, Palmetto Commerce Parkway, Leeds Avenue, Palmetto Commerce Park, Crosspoint IX, I-526, port routing, rail timing, and customer delivery dates.
Around North Charleston’s aerospace assembly, EV motor production, van assembly, copper rod manufacturing, turbo component, bearing, metal fabrication, and automotive supplier work, one order can require copper rod, EV motor parts, aerospace components, machined parts, inspection records, or supplier paperwork before the finished work can turn into a paid invoice.
A shop floor can wait on Palmetto Commerce Parkway shift traffic, I-526 bridge delays, Wando Welch drayage, Hugh K. Leatherman Terminal routing changes, Navy Base Intermodal Facility construction, rail timing, or a delayed aerospace component before the next production step starts. At Crosspoint IX and the Palmetto Commerce Park side, large-block industrial space, dock timing, skilled aerospace labor, EV retraining, and just-in-time parts can all decide whether the next assembly step stays on schedule.
When one material lot is late, one machine is down, one inspection waits, one supplier truck misses the dock time, one rail lift backs up, or one I-526 route changes, the next production step waits too.
If materials are late, the line waits.
Power, rent, supplier invoices, and payroll keep running.
Payroll is Friday. Your customer may still be paying on 30, 60, or 75 day terms.
Orange Commercial Credit factors approved invoices for manufacturers and industrial suppliers across many types of production. A machining invoice may be backed by a purchase order and inspection record, while a packaging order may rely on a packing list and delivery receipt. The paperwork depends on what the customer ordered, what was delivered, and what the customer accepted.
Machining, welding, cutting, forming, fabrication, and assembly orders may be supported by purchase orders, work tickets, packing lists, delivery receipts, inspection records, or signed quality-control records.
Steel, pipe, tube, and fabricated-component suppliers may pay for material and shop labor before the customer pays the invoice. Purchase orders, work tickets, shipping documents, and delivery records can show what was produced and delivered.
Equipment parts, assemblies, repair components, and industrial systems may go through several production steps before shipment. Purchase orders, packing lists, inspection records, and delivery proof may support the completed order.
Manufacturers supplying aerospace or defense-connected customers may work from detailed purchase orders, part specifications, inspection records, packing lists, delivery documents, and customer acceptance records.
Manufacturers may pay for resin, rubber, fiberglass, other materials, labor, and freight before the customer pays. Purchase orders, production records, packing lists, and delivery proof may support the finished order.
Specialty chemical and industrial-material orders may rely on quantity records, shipping documents, delivery records, and customer acceptance showing what was supplied.
Pallet, wood-product, paper, corrugated, and packaging manufacturers may pay for lumber, paper, board, labor, and freight before customers pay their invoices. Purchase orders, packing lists, and delivery receipts may support the completed order.
Food processors and beverage manufacturers may pay for ingredients, packaging, labor, utilities, and delivery before the B2B customer pays. Purchase orders, packing lists, and delivery records can document the completed order.
Concrete products, stone, glass, mineral products, and other manufactured building materials may involve heavy shipments, delivery tickets, shipping records, and customer acceptance. OCC generally excludes most construction receivables, so the invoice still has to qualify as an approved B2B receivable.
Factory-built products, modular products, furniture, fixtures, and other finished goods may be supported by purchase orders, packing lists, shipping records, signed delivery receipts, or customer acceptance records.
Electronics, electrical parts, and technical components may be produced from detailed purchase orders and shipped with packing lists, serial-number records, inspection records, and proof of delivery.
Metal recycling, reprocessing, and other industrial material recovery may produce B2B invoices supported by weights, tickets, delivery records, and customer acceptance documents.
Suppliers want to be paid in 15 to 30 days. Customers take 45 to 60 days and sometimes longer. And they don’t release payment until every piece of paperwork lines up:
By the time you deliver and gather it all, you’ve already cut the checks weeks ago. And you’re still waiting on their payment.
And this is where factoring
helps in manufacturing.
You send the invoice with the paperwork. We review the customer, invoice, and backup. Once the customer is approved, the invoice is verified, and your account is set up, we usually send most of the money within 24 hours. You do not wait 45 to 60 days for your customer to pay before payroll, materials, and supplier bills can be handled.
A pallet manufacturer told us how OCC became part of their growth:
“I’ve been working with OCC for over 9 years now and they’re like a partner for me.
I could not have grown my business this quickly without them!
My account executive is great.
I get credit checks done same day on new business and have never had a complaint from any customer.”
—E.H., President, Pallet Manufacturer
A machine shop owner found that factoring with OCC was "very easy to work with":
“Finding out about OCC has helped keep my business operating with the cash flow I am now receiving. Within a day the money is in my account. During the whole process, OCC was very easy to work with. They made sure I was completely confident and work with me step by step, and the staff is very patient. I would recommend them to any business. Once you start with OCC, you will also be recommending them.”
—Val, Owner and Client Since 2017, Machine Shop
Whether it’s pallets, plastics, machining or food processing, if you’ve already delivered and sent the invoice, you don't need to be waiting 45 to 60 days for payment.
With us, you send the invoice with the backup. We review it and send the money; usually within 24 hours.
Bring one completed B2B invoice. We’ll show the advance, fee, any reserve, and timing before you decide.
Manufacturers in North Charleston and across South Carolina use us when customer terms run long.
Trucking, staffing, and manufacturing are core Orange Commercial Credit industries, but we also factor approved invoices from other B2B businesses.
For these invoices, the goods or services need to have been delivered or completed. We review the commercial customer, the invoice, and the paperwork showing what was provided.
Orange Commercial Credit factors approved B2B invoices from oil, gas, and energy-service companies. Field crews may need to be paid, parts purchased, equipment rented, and travel covered before a commercial customer pays the invoice.
Field-service companies may invoice operators, contractors, industrial businesses, or other commercial customers after crews finish the work. Work orders, service tickets, field reports, or completion records may support the invoice.
Inspection, nondestructive testing, measurement, compliance, and technical-service work may be documented with work orders, service tickets, field reports, test records, or customer acceptance.
Equipment-service companies and parts or supply vendors may buy inventory or pay suppliers before their B2B customers pay. Purchase orders, packing lists, delivery records, or customer acceptance may support the invoice.
Maintenance and repair companies may pay technicians, buy parts, and send equipment or vehicles to the job before the customer pays. Work orders, service tickets, and completion records may document the finished work.
Engineering, project, and technical firms may invoice after a defined service is completed or a project milestone is accepted. The invoice may be supported by the agreement, work records, or customer approval of the completed milestone.
Different energy services can require different paperwork. Before you decide, compare the customer review, paperwork required, advance, reserve if any, fee, and funding timing in writing.
Orange Commercial Credit factors approved invoices from wholesalers, distributors, and B2B suppliers. These businesses may buy inventory, pay freight, and pay warehouse crews before the customer pays for the delivered goods.
A distributor may pay the supplier and freight bill, deliver the goods, and then wait for the commercial customer to pay. Purchase orders, packing lists, and delivery receipts may support the invoice.
Parts, tools, safety products, consumables, materials, and other commercial supplies may be sold on terms to recurring B2B customers. Purchase orders and delivery records can show what was ordered and received.
Distributors may pay suppliers, warehouse crews, carriers, and packaging costs before grocery, restaurant, and other commercial customers pay their invoices.
Equipment, replacement parts, components, and specialty products may be supported by purchase orders, packing lists, delivery records, and customer acceptance documents.
Warehouse, fulfillment, storage, and logistics companies may pay employees, equipment costs, insurance, and transportation expenses before their commercial customers pay.
Different products create different invoice backup. For wholesale and distribution factoring, compare the customer review, delivery or acceptance records, advance, reserve if any, fee, and funding timing in writing.
Orange Commercial Credit can factor approved B2B service invoices even when no physical product changes hands. A service company may pay employees and contractors for weeks of completed work before the commercial customer pays the invoice.
Managed IT, software, network, cybersecurity, data, system implementation, and other technology firms may invoice after recurring services are completed or after a project milestone is accepted.
Engineering, design, testing, quality, technical-support, and project-service companies may bill after completed work or an approved project milestone.
Consulting, management, training, research, and other professional firms may pay employees and contractors before the customer pays for the completed work.
Back-office, administrative, accounting-related, document-processing, and other recurring B2B service companies may invoice commercial customers after the agreed work has been completed.
Companies serving defense, aerospace, industrial, logistics, or other specialized commercial customers may bill for technical or professional work even when the business is not a trucking, staffing, or manufacturing company.
For B2B service invoices, compare what proves the work was completed, what paperwork supports the invoice, the customer review, advance, reserve if any, fee, and funding timing in writing.
Orange Commercial Credit factors approved invoices from many commercial and field-service businesses. Crews may finish the work while payroll, supplies, parts, vehicles, and equipment costs are already due.
Janitorial, facility-maintenance, grounds, and property-service companies may pay crews, buy supplies, and maintain vehicles or equipment before commercial customers pay their invoices.
Commercial security and site-service companies may pay guards and field crews each week while the contract customer pays the invoice later.
Repair, maintenance, installation, and field-service companies may buy parts, pay technicians, and send vehicles or equipment to the job before the commercial customer pays.
Telecom support, network field work, tower-related services, cabling, and other infrastructure work may be documented with work orders, completion records, and customer acceptance.
Orange Commercial Credit can also factor approved invoices from other recurring B2B service companies when the work has been completed and the invoice has supporting paperwork.
For commercial and field-service invoices, compare the customer review, completed-work records, paperwork required, advance, reserve if any, fee, and funding timing in writing before you decide.
Don't see your industry?
If your company delivers goods or completes services for another business and invoices that customer on terms, one customer and one invoice can start the review. We can review the customer and invoice and tell you what information is needed next.
Orange Commercial Credit generally does not factor most construction invoices, third-party medical receivables, or consumer invoices.
Here's another benefit to factoring
you may not be aware of:
If you’re a pallet manufacturer sending a quote, a distributor supplying parts, or a service firm chasing contracts, you’ve heard it:
“Can you give us Net-30?”
Sometimes Net-45. Buyers ask for it every day. And if you can’t offer it, they move on. With factoring in place, you can say yes without tying up your own cash.
Longer terms can:
Some answers below explain common factoring practice, because exact handling can vary by factoring company and written agreement. When we describe Orange Commercial Credit's own process or terms, we say so. For any account-specific term, the written quote and agreement are what matter.
Start here if you want to understand what gets reviewed, when you receive the advance, what happens when your customer pays, and what happens after setup.
What matters most is whether your customer pays, and whether the invoice is clear, verified, and for work that has already been done.
Things like tax liens or pledged invoices can slow things down, but we will talk it through with you.
If we can help, we will say so fast. If not, we will tell you that too. No guesswork.
Call us and we will go over one of your customer’s invoices together.
No. Invoice factoring is not a loan. You sell an invoice for work already done, so there is no new debt.
It is money your customer already owes. Factoring lets you get most of that money sooner, after the customer is approved, the invoice is verified, and your account is set up.
The process starts with completed B2B work, an invoice, and the backup paperwork tied to that work.
In factoring generally, the factor needs to understand the customer, confirm that the invoice represents completed work or delivered goods, and review the backup that supports the amount being billed. The exact review varies by factor, industry, customer, and invoice.
At Orange Commercial Credit, customer approval starts with commercial credit review and payment-history information. Our credit managers use national commercial credit databases. We also verify the invoice and the backup paperwork tied to the completed work.
That backup can look different by industry: trucking may use a rate confirmation, bill of lading or proof of delivery; staffing may use approved timesheets and the service agreement; manufacturing may use a purchase order, packing list, delivery proof, inspection record, or signed QC paperwork.
In factoring generally, the customer's payment completes the next part of the transaction. The factor accounts for the fee and any reserve or remaining balance according to the written agreement.
At Orange Commercial Credit, when your customer's payment posts to our bank, any available reserve releases under the written agreement terms, minus the factoring discount fee.
That is why the written numbers matter before you decide: they should show the advance, any reserve, the fee, and the funding timing for the invoice being reviewed.
Factoring agreements vary, so ask whether the provider requires all eligible invoices, all invoices from a customer, a monthly minimum, or allows selective invoice use.
At Orange Commercial Credit, you choose which invoices to factor; you do not have to factor every invoice. One customer and one invoice can start the review.
Customer approval, invoice verification, and the required backup still apply to the invoice you want reviewed.
No. You choose which invoices to sell. Most clients start with just one, like a $5,000 load that has already been delivered.
Most of our clients are trucking companies, staffing firms, and manufacturers. But we have funded companies across more than 50 industries.
The process works the same for any business that bills other businesses. Orange Commercial Credit does not fund most construction invoices, third-party medical receivables, or consumer invoices.
North Charleston examples of where the work happens:
I-26, I-526, North Charleston intermodal freight, and warehouse docks in Hanahan and Ladson.Staffing: Warehouse and forklift shifts around Palmetto Commerce Park and Palmetto Commerce Park, with workers commuting through North Charleston, Hanahan, and CARTA transit routes..
Manufacturing: North Charleston and North Charleston fabrication work along I-526 and I-26, with parts, metal, and finished goods moving through the Lowcountry production corridors.
At Orange Commercial Credit, our portal shows every invoice and payment: status, paperwork, and credit, so you always know where you stand.
You do not have to wonder
if a payment was posted right.
Your paperwork is handled by our team. Many have been here for years and know how invoice questions, payment questions, and paperwork questions usually get fixed.
At Orange Commercial Credit, you get a dedicated account executive. They know you, your business, and your paperwork.
You are not bounced from rep to rep re-explaining the same invoice. You talk to the same person who knows your account, your invoices, and the questions that need to be answered before money is sent.
A logistics company shared what their experience with OCC has been like:
“We have been with OCC for the last 3 years and have had a great relationship. OCC has been a very important part in our business. With their quick credit information on new prospect customers is the key to eliminate any accounting issues.
"We submit our invoices through their scanning program and are funded same day with no problems.
"We have not had any problems or complaints from our customers as they are very kind and professional to them.
"I highly recommend OCC if you are looking for a reliable and honest Factoring Company.”
—Mary, Operations/Accounting, Logistics Company
In many trucking searches, yes. Freight factoring, trucking factoring, transportation factoring, and freight bill factoring usually refer to the same basic arrangement: a carrier delivers a load, invoices a broker, shipper, or commercial customer, and sells the approved freight invoice to a factoring company instead of waiting for the customer to pay on terms.
The wording can vary, but the comparison is the same. Ask whether the broker or shipper can be approved, what paperwork is needed, what advance is offered, whether a reserve applies, what fee is charged, when funding can go out, and what happens when the customer pays.
In many staffing searches, yes. Staffing factoring, staffing invoice factoring, staffing agency factoring, and payroll funding often describe the same basic arrangement: the staffing agency completes the work, invoices the customer, and sells the approved invoice to a factoring company instead of waiting for the customer to pay.
The terms can vary by provider, but the comparison should start with the customer, approved timesheets, invoice, advance, any reserve, fee, payment instructions, funding timing, agreement terms, invoice choice, and who answers after setup.
No. Invoice factoring starts with completed B2B work, an invoice, the customer, and the backup paperwork tied to that completed work. A loan or line of credit may depend on your business credit, collateral, repayment terms, borrowing limits, and lender requirements.
If a North Charleston search result advertises working-capital loans, equipment finance, purchase-order funding, asset-based lending, or another finance product, compare that offer separately from invoice factoring.
In an invoice factoring arrangement, the customer sends payment according to the factoring company’s written instructions.
That does not automatically mean the factoring company handles every dispute or collection task. Before you sign, ask who verifies the invoice, who answers payment questions, who follows up if payment is late, and who works through a dispute or short pay.
At Orange Commercial Credit, we verify the invoice and the backup tied to the completed work. The written payment instructions show where your customer sends payment.
The invoice amount and the terms you set with your customer do not change because of factoring. What changes is the payment instruction for where the customer sends payment.
We verify the invoice and the backup tied to the completed work. The written payment instructions show where your customer sends payment.
If something is missing from the invoice packet, the review may pause until the required backup is complete. After account setup, customer approval, invoice verification, and required backup, we usually send the advance within 24 hours.
Most of our team has been here ten years or more. They know the paperwork and can answer questions tied to the invoice.
Receivables factoring and accounts receivable factoring usually refer to invoice factoring. “A/R financing” or “A/R funding” can also describe a loan or credit line secured by receivables, so ask whether the company buys the invoice or lends against receivables. Orange Commercial Credit buys approved unpaid invoices.
Use these questions to help understand the written agreement, cost, reserve, payment timing, recourse, minimums, and add-on services.
There is no single industry rule. In factoring, the invoice normally remains outstanding until the customer pays or the invoice is otherwise resolved. What happens to the fee, reserve, recourse period, or other account terms depends on the factor's pricing structure and written agreement.
Before you sign, ask how the fee changes with payment timing, whether a recourse period applies, and what the agreement says happens if the customer is still unpaid after that period.
For an Orange Commercial Credit account, use the written quote and agreement for your actual terms rather than assuming a general factoring practice applies.
In factoring generally, a dispute or short pay is different from a customer simply paying slowly. The outcome can depend on why the customer disputed the invoice, what the supporting paperwork shows, and what the written recourse or non-recourse terms actually cover.
Some agreements may require the business to cure a dispute or take responsibility for an invoice that does not meet the agreement terms. Other credit-loss situations may be treated differently. Do not assume the words recourse or non-recourse answer every situation.
Ask what happens to the advance, any reserve, the fee, and the open invoice if the customer disputes the work, claims a shortage, takes a deduction, or pays less than the invoice amount.
Ask what type of customer nonpayment is covered, what happens after a dispute or short pay, whether an unpaid invoice must be replaced or repurchased, what minimums apply, which invoices you may choose, and what happens when the agreement ends.
Orange Commercial Credit offers a 90-day factoring agreement, no setup fee, no minimum number of invoices, and invoice choice. Ask us to show how those terms apply to your customer and invoice in the written proposal.
Factoring fee range: 1.25% - 5% (varies by deal).
The discount fee is a percentage of the invoice. How much depends on your industry, how fast your customer pays, your customer’s credit, and the dollar amount of invoices you sell us.
You always see the cost up front before you decide.
If a reserve applies, ask how it is handled after your customer pays and what charges, if any, apply under the written agreement.
Ask for any transfer or delivery charges to be shown in writing before you decide. Your bank may also have its own receiving charges.
This list is here so the numbers do not surprise you later.
If you only ask three, start here:
Full checklist:
1) Advance rate:
This is what you get up front. A lower advance can mean you are waiting on more of your own money until your customer pays.
2) Factoring fee:
Ask what the fee covers: per 10 days, per 30 days, daily, or flat. If it is tiered, ask for the full tier schedule in writing.
3) Recourse period (how long the invoice can stay open):
Ask what happens if your customer still has not paid by then.
4) Recourse or non-recourse terms:
Ask what the terms make you responsible for if the customer does not pay, disputes the invoice, short-pays it, or the paperwork does not match.
5) Customer credit concentration limits (how much they will fund for one customer):
Ask what the limit is if one customer is a big share of your billing.
6) Reserve:
This is what is held back and released when your customer pays, minus the fee. Ask when reserves are released and how those are processed.
7) “Other” delivery fees:
Ask whether any transfer or delivery charges are separate from the factoring fee and have each charge shown in writing. Your bank may also charge a receiving fee.
8) Minimums or commitment fees:
Ask if you pay a fee when you do not factor enough in a slow month.
9) What other fees do you charge?
Ask for a full list: setup, portal, monthly fees, invoice fees, due diligence, termination, buyout, or anything that can show up later.
10) Contract term:
Ask how long you are agreeing to, and how it renews.
• Initial term length
• Renewal term length
11) What notice do you need to stop factoring?
Ask what proper notice means and when it must be given.
• If you are moving to another factor
• If you just do not need factoring anymore
If they will not put it in writing, you cannot really compare it.
Yes. Those services can matter, but they should not replace the factoring review. Ask whether the broker or shipper can be approved, whether the load paperwork supports the invoice, and whether the advance, any reserve, fee, payment instructions, and funding timing are shown in writing.
If a factoring offer includes a fuel card, fuel bundle, mobile app, load board, dispatch service, 24/7 funding, or other carrier tool, ask whether that extra service changes the fee, minimums, invoice choice, agreement terms, switching terms, or who answers after setup.
Some trucking factoring companies require monthly volume minimums or expect you to factor every invoice from certain customers. Others may let you choose which invoices to factor. Ask before you sign.
Orange Commercial Credit lets you choose which invoices to factor, and you do not have to factor every invoice. One customer and one invoice are enough to start the review and see whether the written numbers work.
Some staffing factoring companies require monthly volume minimums or expect you to factor every invoice from certain customers. Others may let you choose which invoices to factor. Ask before you sign.
Orange Commercial Credit lets you choose which invoices to factor, and you do not have to factor every invoice. One customer and one invoice are enough to start the review and see whether the written numbers work.
They are different services. Back-office payroll support may help with payroll processing, tax filing, onboarding, timekeeping, or administrative work. Invoice factoring buys approved unpaid invoices so your staffing agency can have money before the customer pays.
Before you choose, ask whether the provider is buying the invoice or providing payroll administration. Also ask whether any back-office service changes the fee, minimums, invoice choice, agreement terms, switching terms, or who answers after setup.
Use these questions to help compare provider types, local versus national options, industry fit, written quotes, and who will actually service the account.
Compare the advance rate, factoring fee, any reserve, customer approval process, paperwork needed, payment instructions, funding timing, agreement terms, invoice choice, minimums, and who answers after setup.
A national ranking, local-office address, fast-funding headline, app, fuel-card offer, or low-fee claim does not show the full quote. Start with one real customer and one real invoice, then compare the written numbers.
You can start with one customer and one invoice. It also helps to know your industry, the invoice amount, your typical monthly invoice volume, the customer’s payment terms, and what paperwork supports the completed work.
Monthly volume and payment terms can help you compare quotes, but you do not need everything ready before the first call.
No. Trucking, staffing, and manufacturing are our biggest groups, but we also help many other B2B companies, including:
Plus other businesses that invoice customers on 30–75 day terms.
Yes. Orange Commercial Credit is a national independent direct invoice factoring company serving North Charleston, Charleston County, the Lowcountry, South Carolina, and businesses nationwide.
We review the customer, invoice, and backup paperwork, send the advance after approval and verification, receive the customer’s payment, and service the account after setup.
One customer and one invoice are enough to start the review and see whether the written numbers work.
No. Orange Commercial Credit serves North Charleston businesses without requiring an office visit.
A factoring company does not need a North Charleston office to factor approved invoices for a North Charleston business.
That is because customer approval is based on commercial credit review, payment-history information, invoice verification, and the backup paperwork tied to the completed work, not on the factoring company’s address.
Before you decide, we show the advance, reserve, fee, payment instructions, and funding timing in writing.
North Charleston results can include North Charleston or Charleston-area pages, statewide South Carolina pages, national direct factors, freight and staffing specialists, ranking or review pages, brokers or referral listings, and commercial-finance companies offering a different product. The listing type tells you where to start; the written quote tells you what applies to your customer and invoice.
Compare the advance, any reserve, fee, paperwork, funding timing, and who answers after the invoice funds. Ask for those numbers and terms in writing for one real customer and one real invoice. That gives you something concrete to compare without relying on a ranking or headline.
Compare the written quote first. It should show who reviews the customer, who verifies the invoice, what advance is offered, whether a reserve applies, what fee applies, where the customer sends payment, and who answers after setup.
A broker, marketplace, matching service, or advisory service may introduce you to one or more factoring companies. A direct factoring company reviews the customer and invoice, sends the advance after approval, receives the customer’s payment, and services the account.
Ask who actually funds the invoice, whose agreement you would sign, how the intermediary is paid, who services the account, and who answers after setup.
Orange Commercial Credit is a direct factoring company. We review the customer and invoice, show the written numbers, send the advance after approval and verification, receive the customer’s payment, and service the account.
Orange Commercial Credit does not fund most construction invoices, third-party medical receivables, or consumer invoices. If a North Charleston search result advertises construction factoring, medical receivables, or consumer receivables, compare that offer separately from invoice factoring for completed B2B work.
For a North Charleston business that invoices B2B customers on terms, the review starts with the customer, invoice, and backup paperwork tied to the completed work.
Yes, when the company invoices B2B customers on terms, the customer can be approved, and the invoice can be verified. That can include technology-related B2B service providers, IT staffing, office-service companies, industrial service companies, and other commercial service businesses. The review may include the invoice, service agreement, purchase order, work ticket, customer approval, or other backup tied to the completed work.
Yes. Orange Commercial Credit provides freight factoring and trucking factoring for North Charleston, the Lowcountry, and South Carolina carriers when the broker or customer is approved, the freight invoice is verified, and the backup paperwork supports the completed load.
That paperwork may include the invoice, rate confirmation, bill of lading, POD, lumper receipt, detention backup, accessorial support, port paperwork, drayage paperwork, intermodal paperwork, or other freight paperwork tied to the completed load.
For port freight, drayage, intermodal, container trucking, owner-operators, and small fleets, compare: broker or customer review, invoice packet review, advance, any reserve, fee, funding timing, customer notice, and who answers after setup.
Once the broker or customer is approved, the invoice packet is verified, and the account is set up, Orange Commercial Credit usually sends most of the money within 24 hours.
Compare the advance rate, factoring fee, any reserve, broker or shipper approval, paperwork needed, payment instructions, funding timing, recourse or non-recourse wording, monthly minimums, invoice choice, and who answers after setup.
A fast-funding claim, app, fuel-card offer, load-board integration, or 24/7 funding headline does not show the full quote. The written quote should show whether the broker, delivered load, invoice packet, fee, any reserve, and agreement terms match the freight invoice you need reviewed.
Yes, through invoice factoring. Orange Commercial Credit is not a payroll processor, PEO, payroll software company, recruiting firm, or back-office staffing company. We buy approved unpaid B2B invoices so North Charleston staffing, warehouse, logistics, port-support, aerospace, automotive, manufacturing, healthcare-support, technical, and light-industrial staffing companies can have money for payroll before customers pay.
The review starts with one customer, one invoice packet, and the backup paperwork tied to the completed work. For staffing companies, that usually means approved timesheets, the invoice, and the service agreement or customer approval needed to verify the work.
Once the customer is approved, the invoice and timesheets are verified, and the account is set up, we usually send most of the money within 24 hours. Staffing and manufacturing advances can be as high as 90%.
Compare the advance rate, factoring fee, any reserve, customer approval process, approved-timesheet review, payment instructions, funding timing, monthly minimums, invoice choice, agreement terms, and who answers after setup.
A high-advance claim, same-day funding headline, back-office service, payroll software offer, or low-fee quote does not show the full agreement. The written quote should show whether the customer, invoice, approved timesheets, fee, any reserve, and agreement terms match the way your agency runs payroll.
Yes. We provide manufacturing invoice factoring for North Charleston and South Carolina manufacturers, port-support suppliers, aerospace suppliers, automotive suppliers, logistics and warehouse suppliers, industrial service companies, distributors, and other B2B companies when the customer is approved and the invoice can be verified.
Backup paperwork may include a purchase order, bill of lading, packing list, delivery proof, signed QC paperwork, work ticket, job ticket, vendor approval, warehouse delivery paperwork, or other support tied to completed work.
Once the customer is approved, the invoice is verified, and the account is set up, we usually send most of the money within 24 hours. Staffing and manufacturing advances can be as high as 90%.
We can review approved B2B invoices for North Charleston port-support, warehouse, logistics, and industrial service work when the customer, completed work, invoice, and required backup can be verified. The paperwork may include a service agreement, purchase order, work ticket, delivery proof, bill of lading, or other customer approval tied to the invoice.
The work is done. The payment is still on terms.
We get it.
There’s no setup fee. Before you decide, we show you the written numbers and the next step for the customer and invoice you want reviewed.
If you decide to move forward, the agreement is a 90-day factoring agreement with no minimum number of invoices required.
It's there when you need it. You’re just giving yourself room to try it and see how it feels.
The agreement lays out the basics:
After account setup, customer approval, invoice verification, and required backup, we usually send the advance within 24 hours.
A staffing owner put it this way:
“I can always count on them to send me funds when I need it.”
—George, Owner and Client Since 2016, Staffing Company
No minimum invoice count. You decide when to use it.
You also get a dedicated account executive who knows your business and picks up when you call, answering your questions on the spot.
And you can log in any time day or night to check on balances and invoices.
If it makes sense, great. If not, you’ll still leave knowing more than you did before.
One intermodal owner described what funding looked like after setup:
“We submit our invoices almost daily using their scanning program, and know that when we submit before the deadline we get same day funding.”
—Mike, President Intermodal Transportation & Warehousing Company, and Client Since 2006
Once the invoice is approved and the account is set up, we usually send the advance within 24 hours. Payroll runs, fuel gets bought, and shop bills get paid.
That’s why we tell owners:
if the numbers make sense, you can decide from there.
Most owners start with just one invoice. That is enough to see how the numbers work.
In the end it always comes
back to the same thing:
one customer,
one invoice,
one call.
Call with one customer name and one invoice in mind. We’ll tell you what paperwork we need, review whether the customer can be approved, and show the advance, fee, any reserve, and timing before you decide.
For a real conversation:
1-800-231-3878
Independent and privately held
since 1979.
No setup fee, no minimum invoice count, and you talk to a person who knows your account.
🌙
After hours? No problem.
After hours, or if you’d rather not call, fill out this form and we’ll call you back.
Related South Carolina factoring company pages